Independent M&A case study · Public information only
MARA × Soluna: buy the power, not the company
Should MARA bid for Soluna Holdings to own renewable-powered capacity in Texas? Updated to the 14-Oct-2026 close, the answer is still no on the equity — and the value worth having has moved from an unbuilt Dorothy 2 to the Dorothy Energy Campus.
Recommendation
$40M cash + $10M contingent
Dorothy Energy Campus: Briscoe wind, 1A/1B, +50 MW rights
Campus bid NPV
+$14.3M
At the $40M + $10M bid
Walk-away price
$60.9M
4.7× 2027E EBITDA
Whole-company bid
–$277.8M
30% premium, preferred redeemed · Reject
Not prepared for, reviewed by, or affiliated with MARA Holdings, Soluna Holdings, or any employer or client. Not investment advice. All figures in US$; "$M" means millions.
Recommendation
MARA should not bid for Soluna’s equity. Instead it should offer $40M in cash plus $10M contingent for the Dorothy Energy Campus: the Briscoe wind farm (149.85 MW), the energised Dorothy 1A/1B halls (50 MW) and the rights to Soluna’s 50 MW load-increase request. MARA should walk away above $60.9M.
| Headline | Value |
|---|---|
| NPV of the recommended bid at a 10.5% WACC | +$14.3M |
| Walk-away price (breakeven all-cash value to MARA) | $60.9M |
| Unlevered IRR, before the expansion option | 13.7% |
| NPV at MARA’s own 17.0% cost of equity | +$2.1M |
| Breakeven WACC | 18.6% |
| Headline price / 2027E campus EBITDA | $50.0M / $10.6M = 4.7x |
| NPV of a whole-company cash bid (30% premium, preferred redeemed) | ($277.8M) |
Four facts drive the call:
- Dorothy 2 is built, so the 2024 deal no longer exists. Dorothy 2 (48 MW) was energised in November 2025. Spring Lane Capital holds the Class B interest and takes 92.5% of distributable cash until it reaches an 18% IRR.
- Soluna cannot cover its overhead. Normalised site cash margin is $22.7M a year, against $23.0M a year of cash corporate opex. Q2-26 Adjusted EBITDA was ($1.6M).
- The preferred makes control expensive. Par plus arrears on the 9% Series A preferred comes to $163.7M at an assumed 31-Dec-2026 close, against $51.7M at market. Conversion on a change of control is capped at 0.2817 common shares per preferred share, so holders would keep their claim, and a clean takeout has to pay it in full.
- The campus fits MARA’s 2027-28 needs. It brings owned wind, energised halls and a path to 50 MW more. MARA’s main third-party hosting contracts expire between 3Q27 and 1Q28.
1. What changed since March 2024
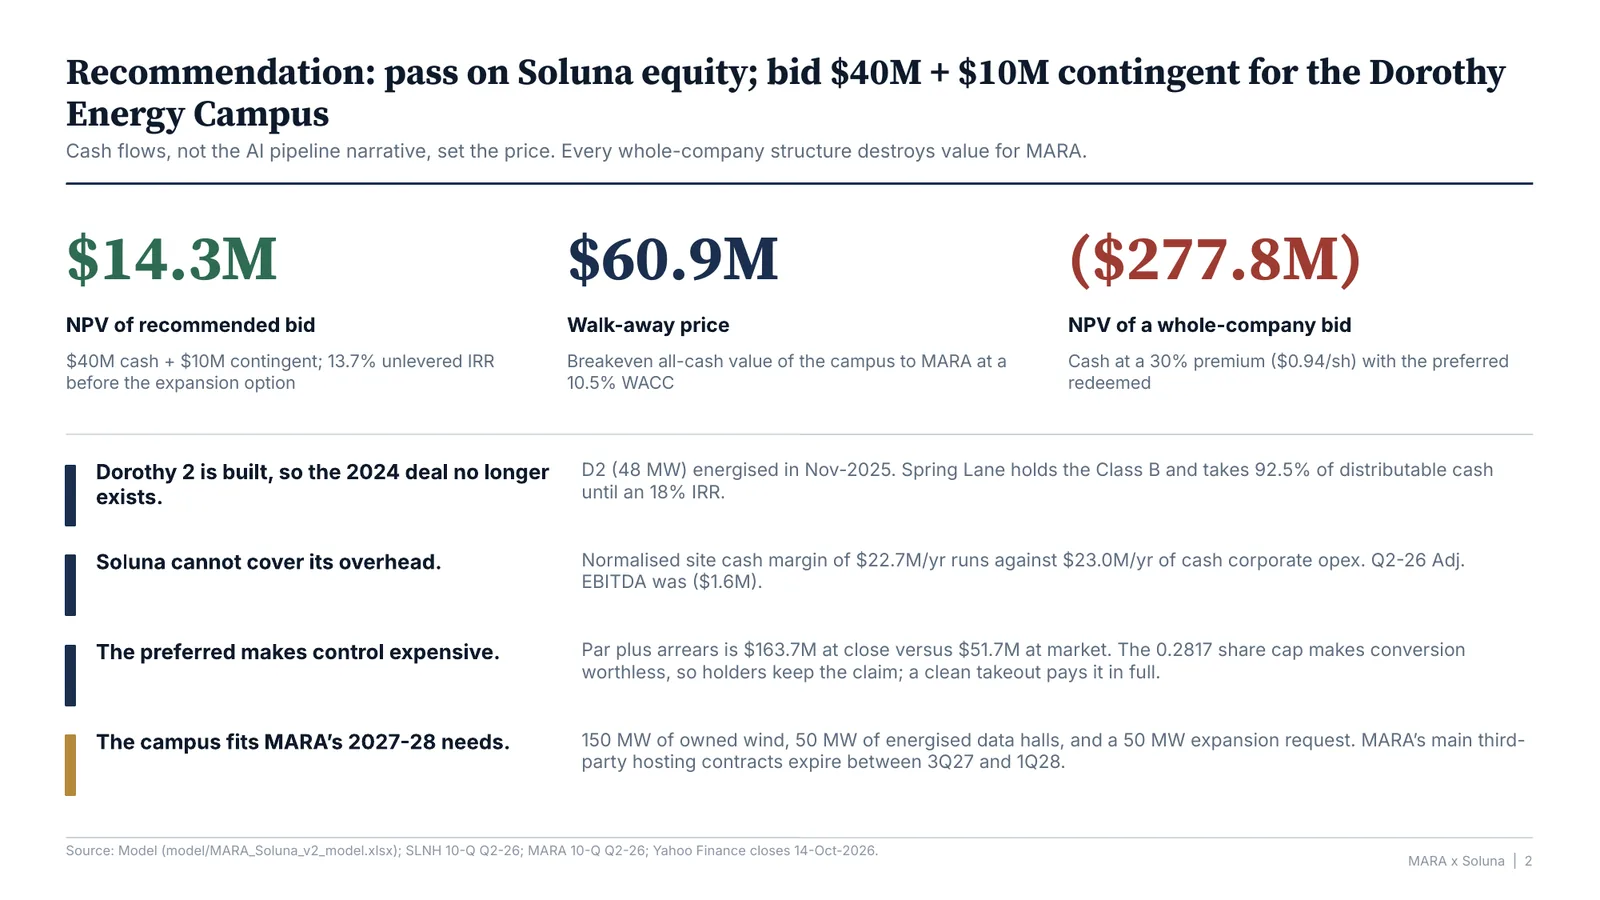
Both companies have moved from building bitcoin sites to chasing AI power.
Soluna
- Nov-25: Dorothy 2 completed and fully contracted.
- Apr-26: bought Briscoe Wind (150 MW) for $53.0M and Spring Lane’s 85.4% of Dorothy 1A for $16.5M.
- May-26: bought Navitas’ 49% of Dorothy 1B for $8.8M, so Dorothy 1 is now 100% owned.
- Jun-26: formed a Kati 2 AI joint venture with Metrobloks.
- Sep-26: completed Kati 1 (83 MW), bringing operating capacity to 206 MW. ERCOT conditionally classified the Kati campus as Base Load in its Batch Zero process.
MARA
- Jan-26: bought the Meerkat data centre (42 MW, Nebraska) for $25.2M.
- Feb-26: formed a joint platform with Starwood Digital Ventures.
- Apr-26: agreed to buy Long Ridge (485 MW CCGT) at about $1.5B of EV. It had not closed as of the Q2-26 10-Q.
- Jul-26: agreed the HIF Matagorda deal: 2 GW of powered land for up to $600M in milestone payments.
The v1 thesis was to buy Dorothy 2 before it was built, for $6.0M (NPV +$3.6M). That deal is now obsolete. Every alternative below was re-tested against today’s capital structure and MARA’s current strategy.
2. Soluna today: 206 MW operated, about 95 MW owned
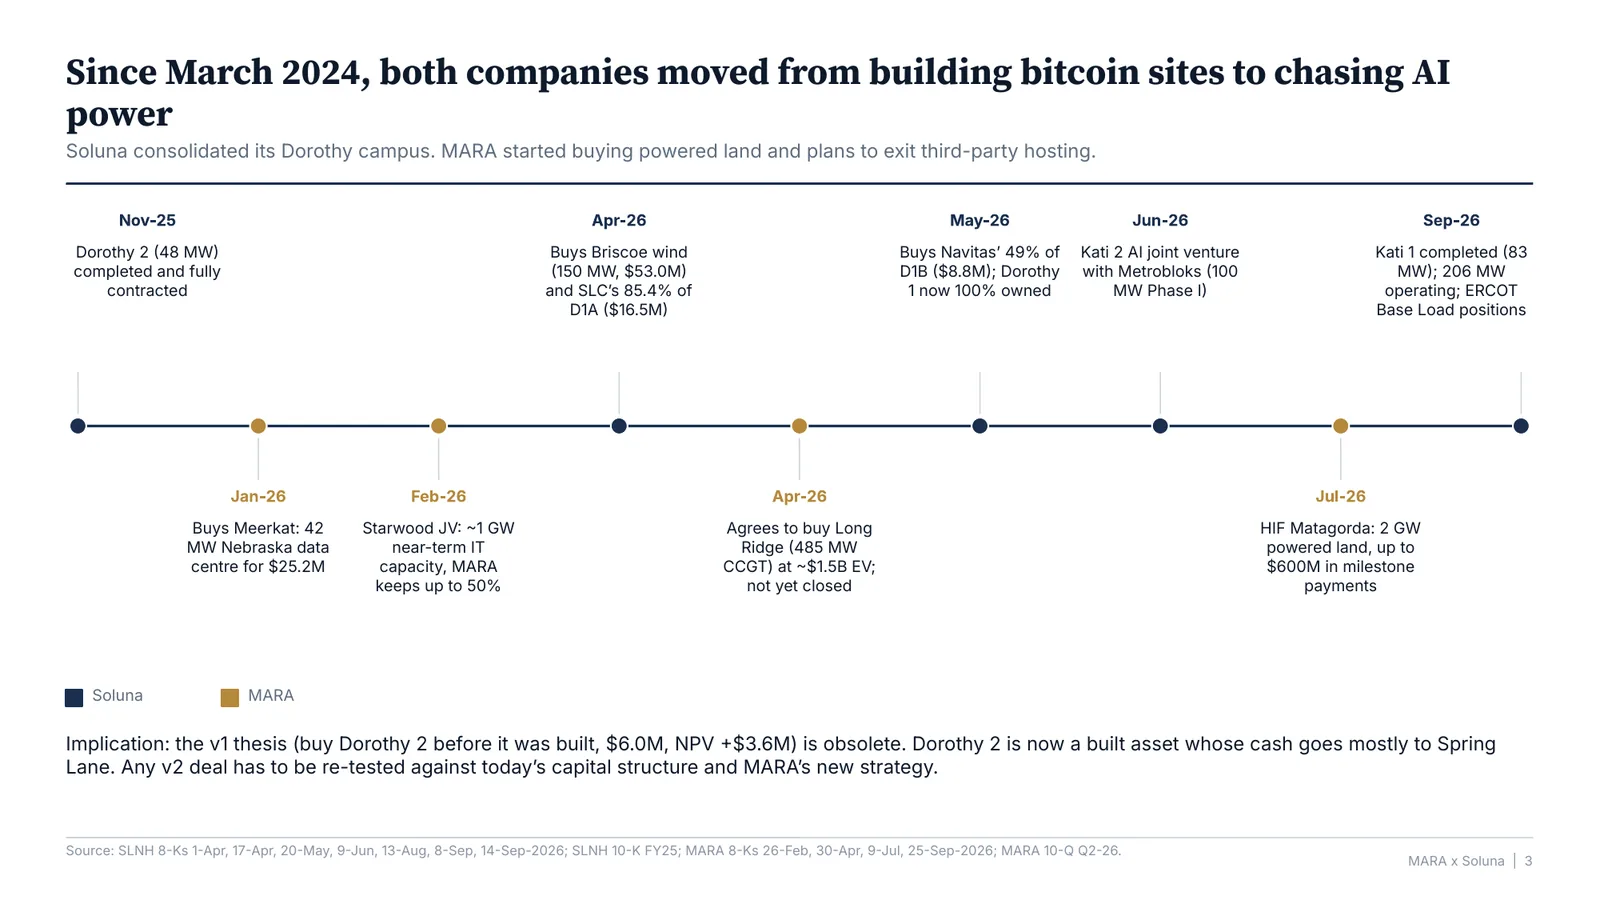
Spring Lane’s Class B preference captures most of the cash from Dorothy 2 and Kati 1 until its hurdle IRR is met. On that basis, Soluna’s attributable capacity is 94.8 MW. The Kati 1 split is an assumption: 7.5% plus 92.5% x 13%.
| Metric | Value |
|---|---|
| Operating capacity (Sep-26) | 206 MW |
| Attributable capacity | 94.8 MW |
| Briscoe wind (owned) | 149.85 MW |
| Q2-26 revenue / LTM revenue | $15.1M / $42.1M |
| Q2-26 gross profit | $0.8M |
| Q2-26 Adj. EBITDA | ($1.6M) |
| Q2-26 net loss | ($22.6M) |
| Pro forma cash (30-Jun + $23.6M ATM - $19.1M Generate prepayment) | $117.9M |
| Development pipeline | 6.3 GW |
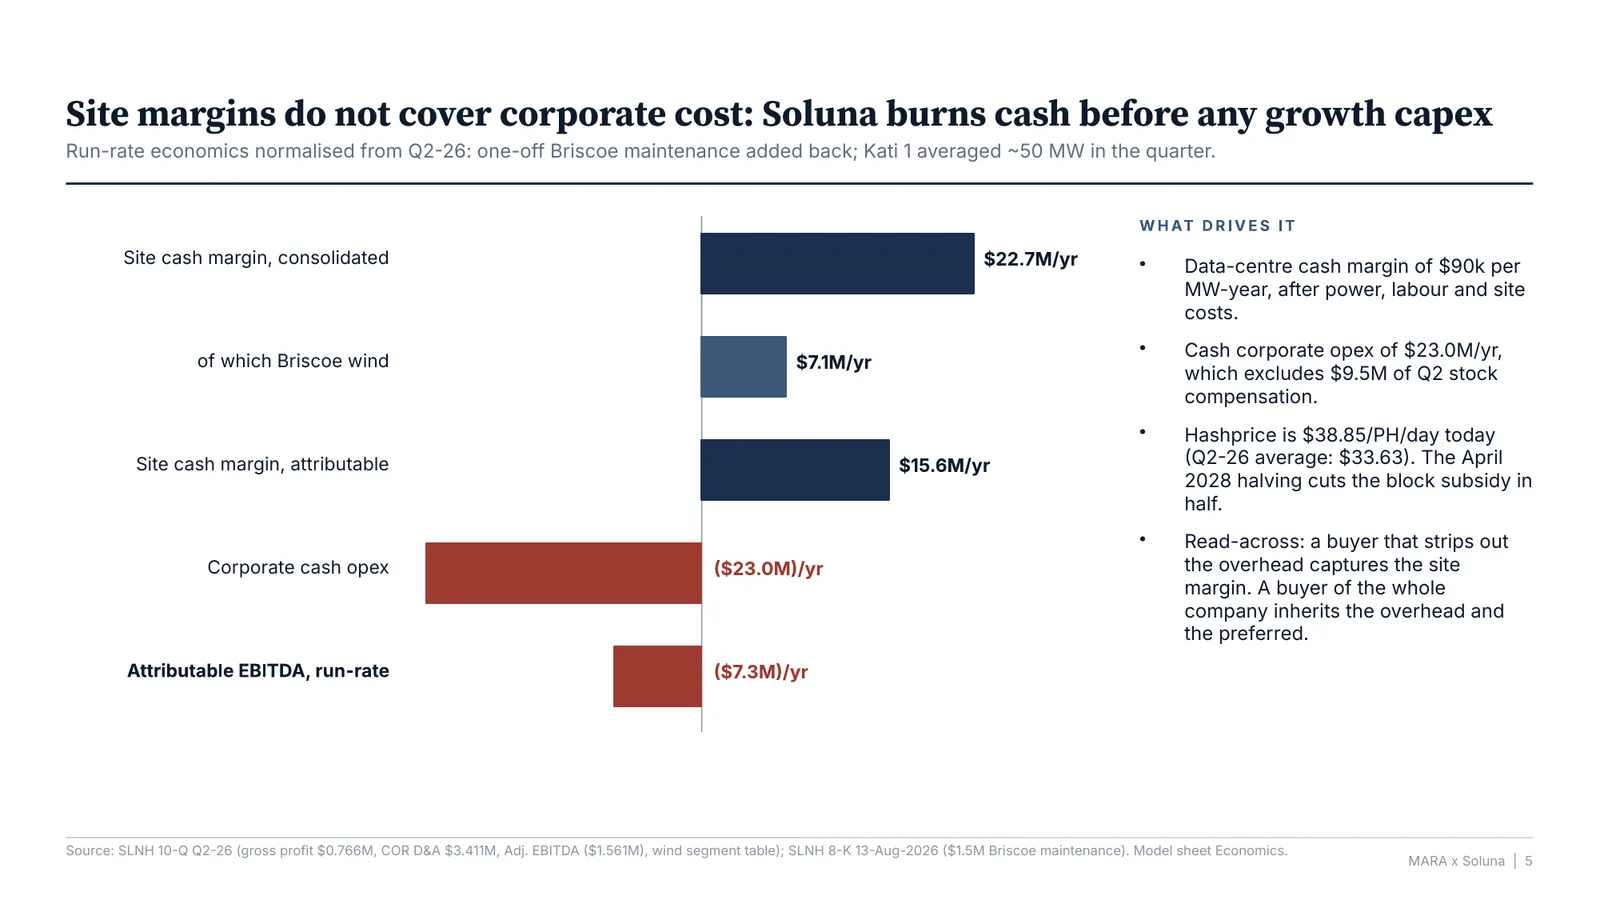
Site economics. The run-rate is normalised from Q2-26: the one-off $1.5M Briscoe maintenance charge is added back, and Kati 1 is assumed to have averaged about 50 MW in the quarter.
- Site margin: the data centres earn about $90k per MW-year after power, labour and site costs. Consolidated site cash margin is $22.7M a year, of which Briscoe wind is $7.1M. The attributable share is $15.6M.
- Overhead: cash corporate opex is $23.0M a year, before $9.5M of Q2 stock compensation. That leaves attributable run-rate EBITDA of about ($7.3M) a year.
- Hashprice and halving: hashprice is $38.85/PH/day (Q2-26 average: $33.63). The April 2028 halving cuts the block subsidy in half.
The read-across is that a buyer who strips out the overhead captures the site margin. A buyer of the whole company inherits both the overhead and the preferred.
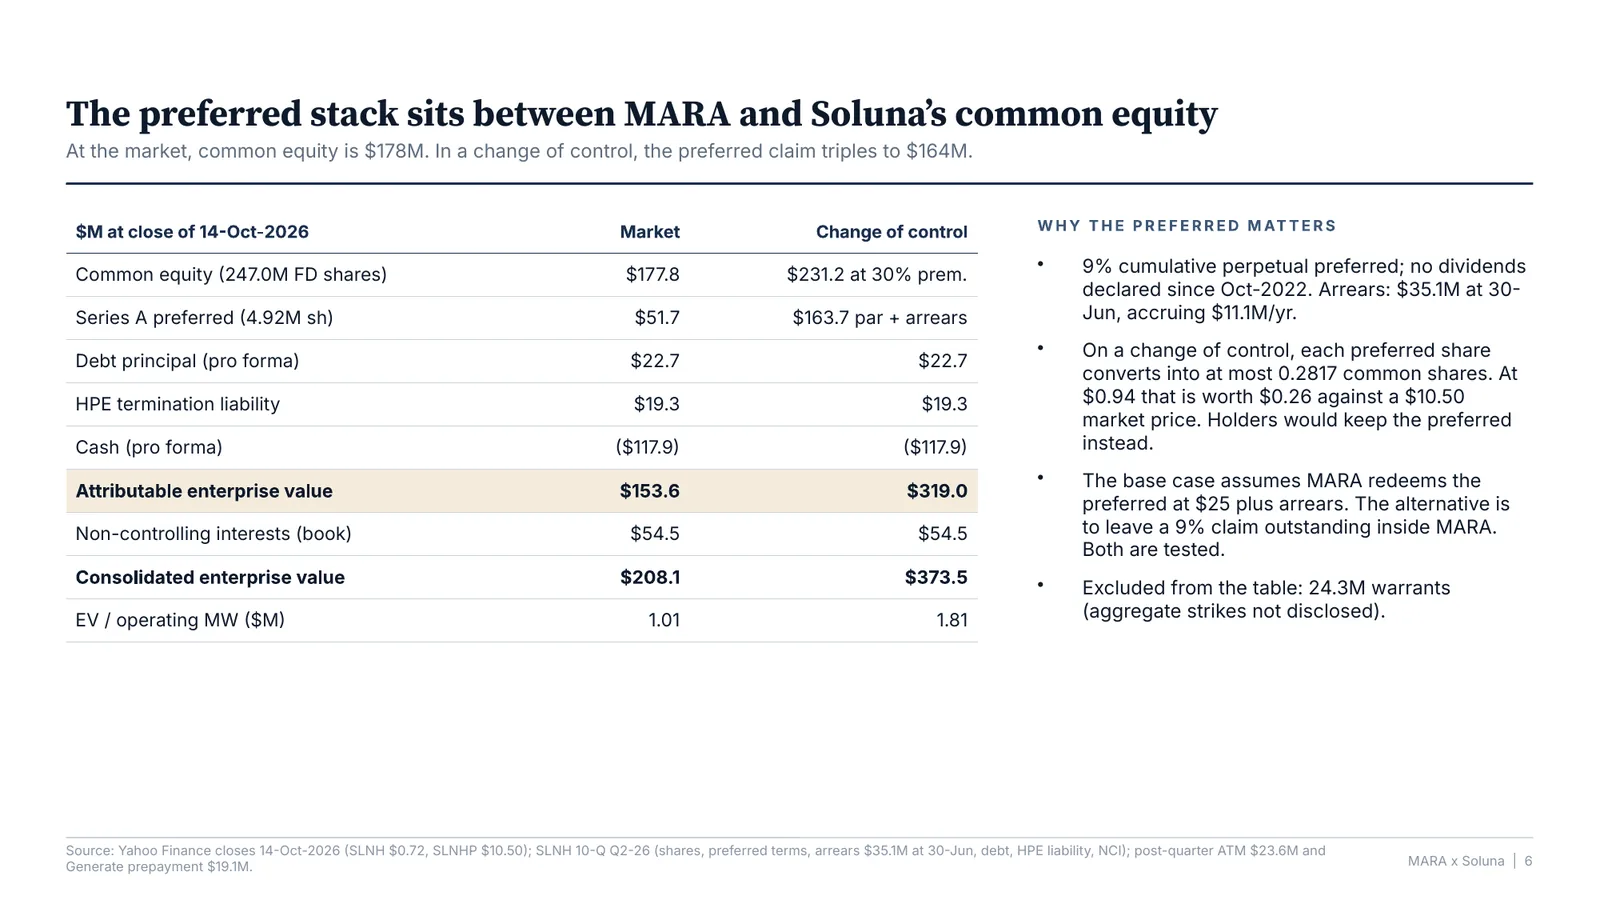
3. Capital structure: the preferred sits between MARA and the common
| $M, close of 14-Oct-2026 | Market | Change of control |
|---|---|---|
| Common equity (247.0M FD shares) | 177.8 | 231.2 at a 30% premium ($0.94) |
| Series A preferred (4.92M shares) | 51.7 | 163.7 (par + arrears) |
| Debt principal (pro forma) | 22.7 | 22.7 |
| HPE termination liability | 19.3 | 19.3 |
| Cash (pro forma) | (117.9) | (117.9) |
| Attributable EV | 153.6 | 319.0 |
| Non-controlling interests (book) | 54.5 | 54.5 |
| Consolidated EV | 208.1 | 373.5 |
| EV per operating MW | $1.01M | $1.81M |
The preferred
- It is a 9% cumulative perpetual preferred, and no dividends have been declared since October 2022. Arrears were $35.1M at 30-Jun-2026 and accrue at $11.1M a year.
- At the $0.94 offer, the 0.2817 conversion cap is worth $0.26 per preferred share, against a $10.50 market price.
- The base case assumes MARA redeems the preferred at $25 plus arrears. The specific redemption mechanics on a change of control were not verified.
Excluded from the share count
- 24.3M warrants are excluded because their strikes are not verified. They are assumed to be out of the money at $0.72.
4. Valuation of Soluna
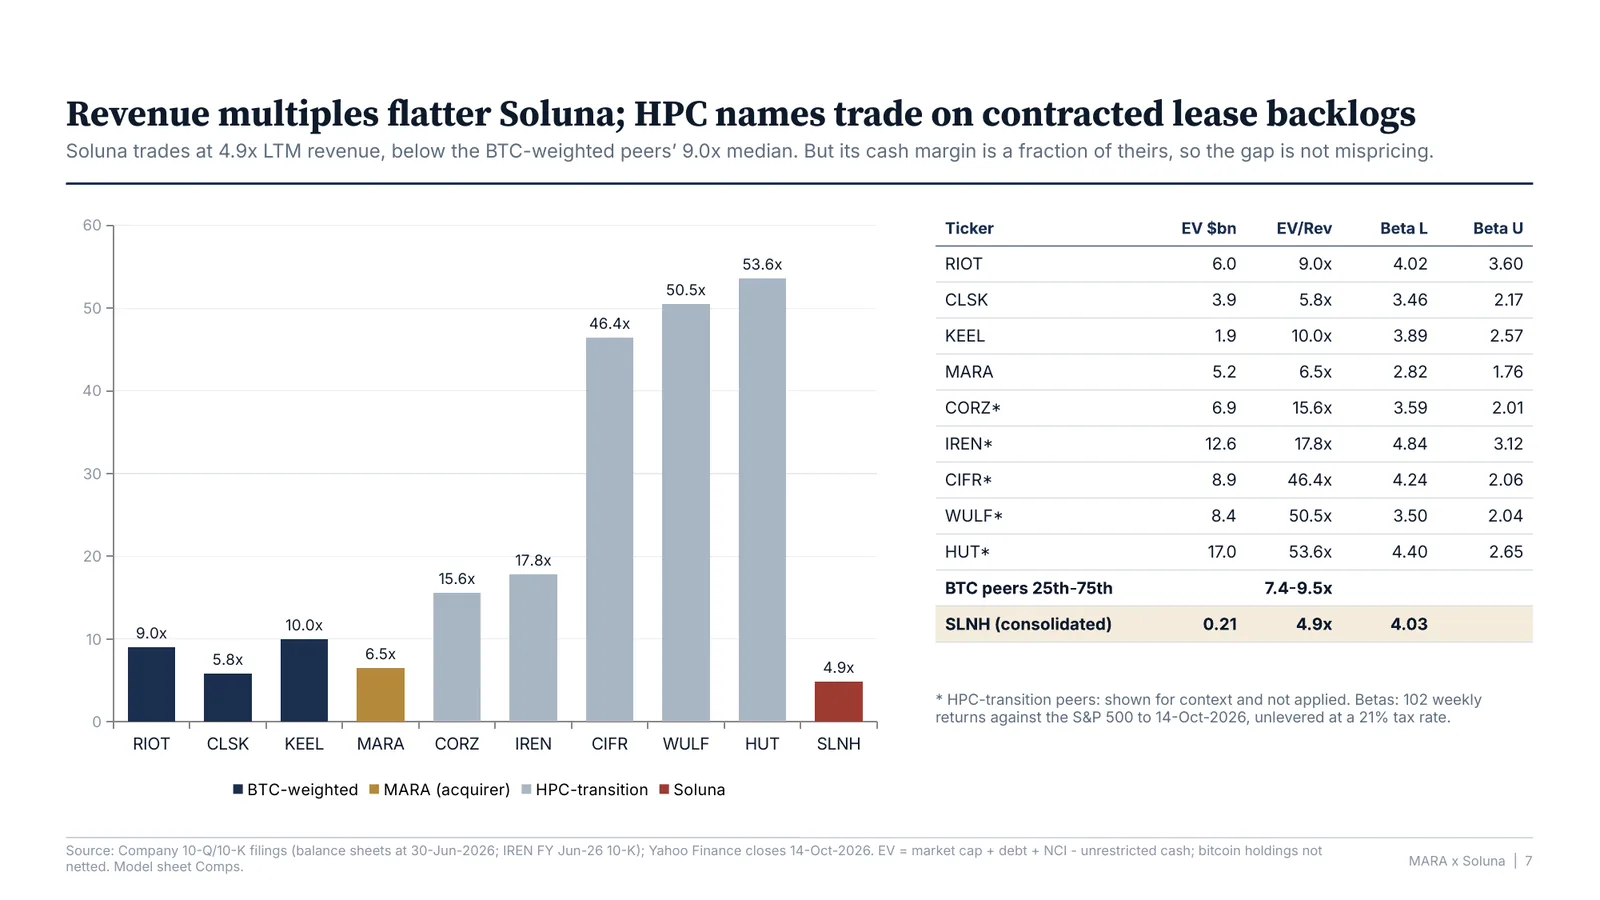
Trading comps. Prices are 14-Oct-2026 closes and balance sheets are at 30-Jun-2026. EV is market cap plus debt plus NCI less unrestricted cash; bitcoin holdings are not netted.
| EV/LTM revenue | |
|---|---|
| BTC-weighted peers: RIOT, CLSK, KEEL, MARA | 25th-75th percentile 7.4x-9.5x (median 9.0x) |
| HPC-transition peers: CORZ, IREN, CIFR, WULF, HUT | 15.6x-53.6x (context only; they trade on contracted lease backlogs) |
| Soluna, consolidated | 4.9x |
Soluna’s cash margin is a fraction of the peers’, so the gap to the peer multiple is not mispricing.
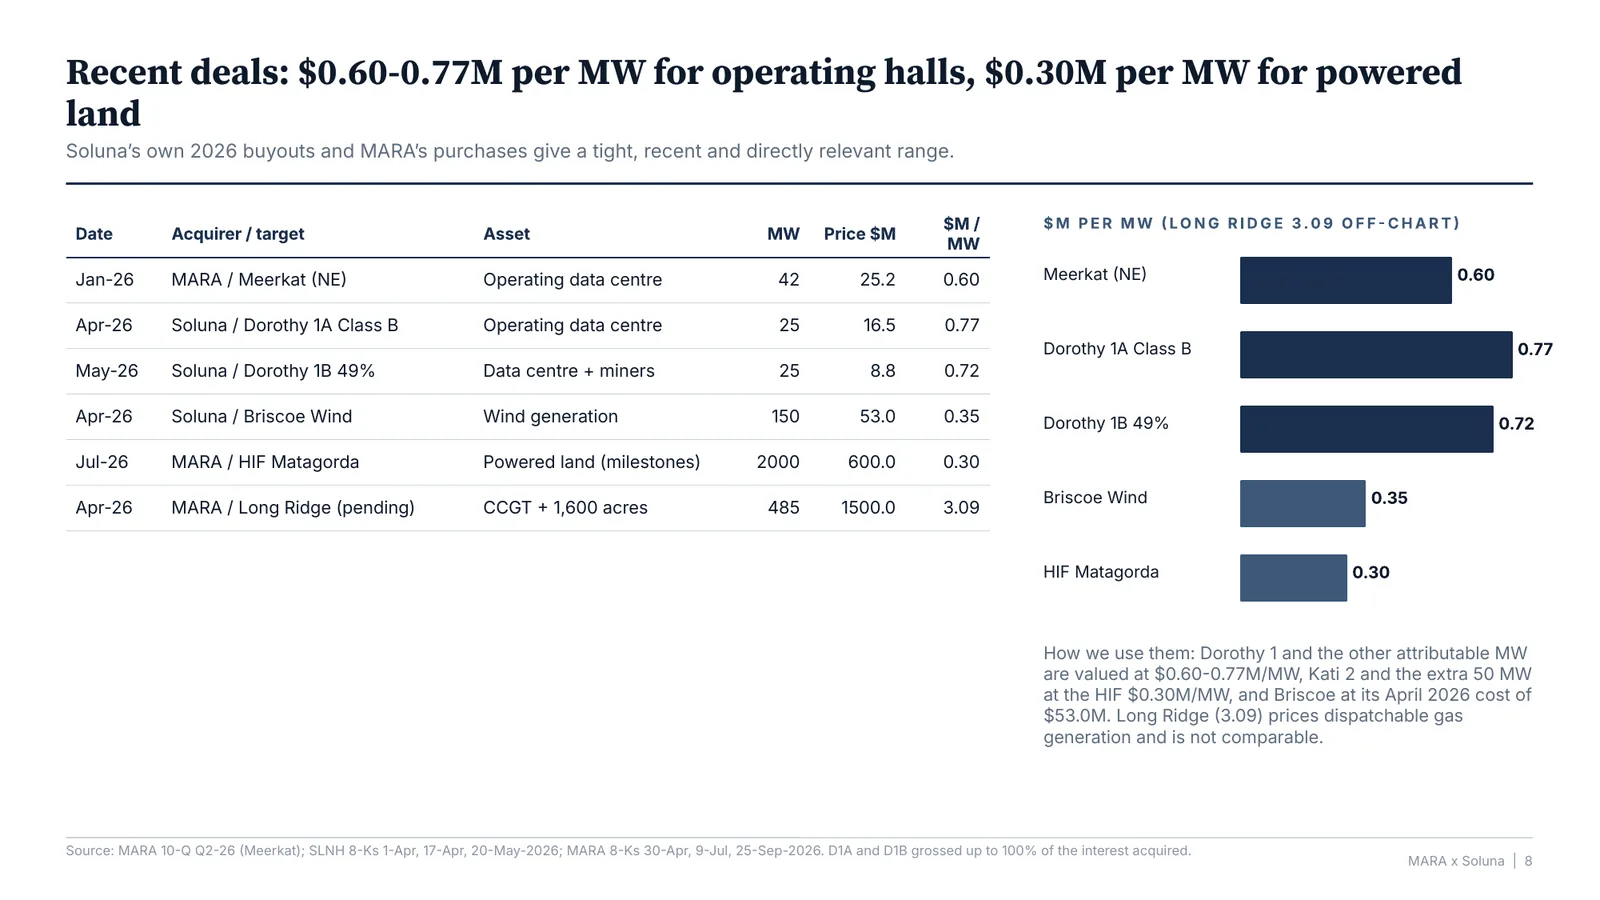
Precedents. These are recent and directly relevant:
- Operating halls, $0.60-0.77M per MW: Meerkat ($0.60M), Dorothy 1A Class B ($0.77M) and Dorothy 1B 49% ($0.72M).
- Wind: Briscoe at $0.35M per MW.
- Powered land: HIF Matagorda at $0.30M per MW.
- Long Ridge ($3.09M per MW) prices dispatchable gas generation and is not comparable.
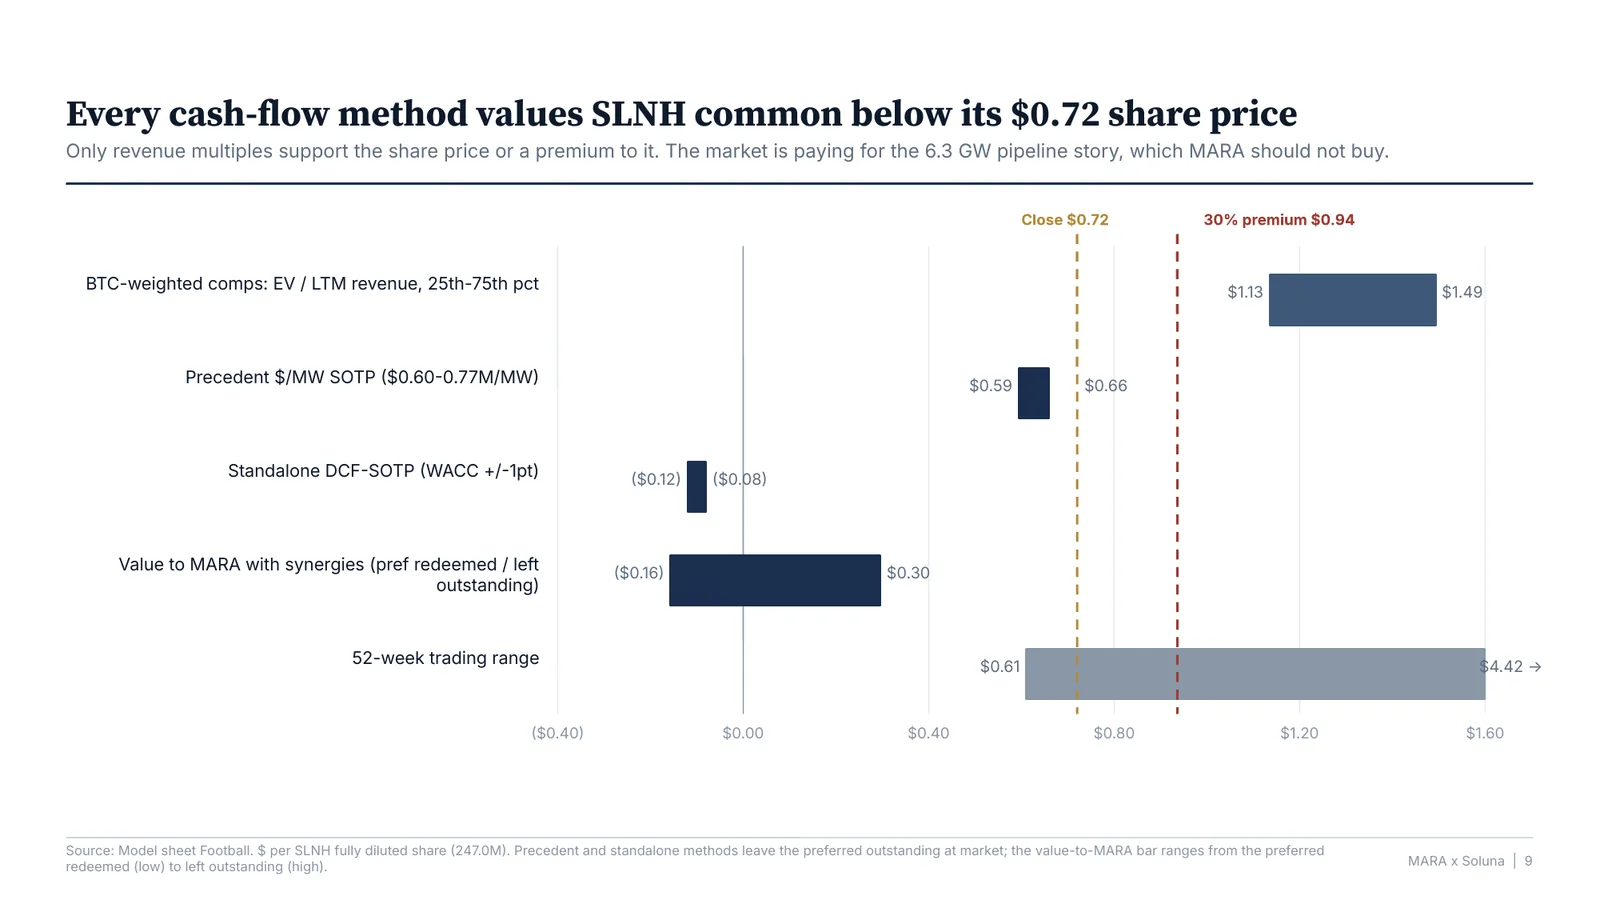
Football field, $ per SLNH share
| Method | Low | High |
|---|---|---|
| BTC-weighted comps (EV/LTM revenue, 25th-75th percentile) | 1.13 | 1.49 |
| Precedent $/MW SOTP | 0.59 | 0.66 |
| Standalone DCF-SOTP (WACC ±1 pt) | (0.12) | (0.08) |
| Value to MARA with synergies (preferred redeemed / left outstanding) | (0.16) | 0.30 |
| 52-week trading range | 0.61 | 4.42 |
| Reference: close / 30% premium | 0.72 | 0.94 |
Every cash-flow method values the common below the $0.72 share price. Only revenue multiples support the price or a premium to it. The market is paying for the 6.3 GW pipeline story, and MARA should not buy it.
5. Alternatives tested
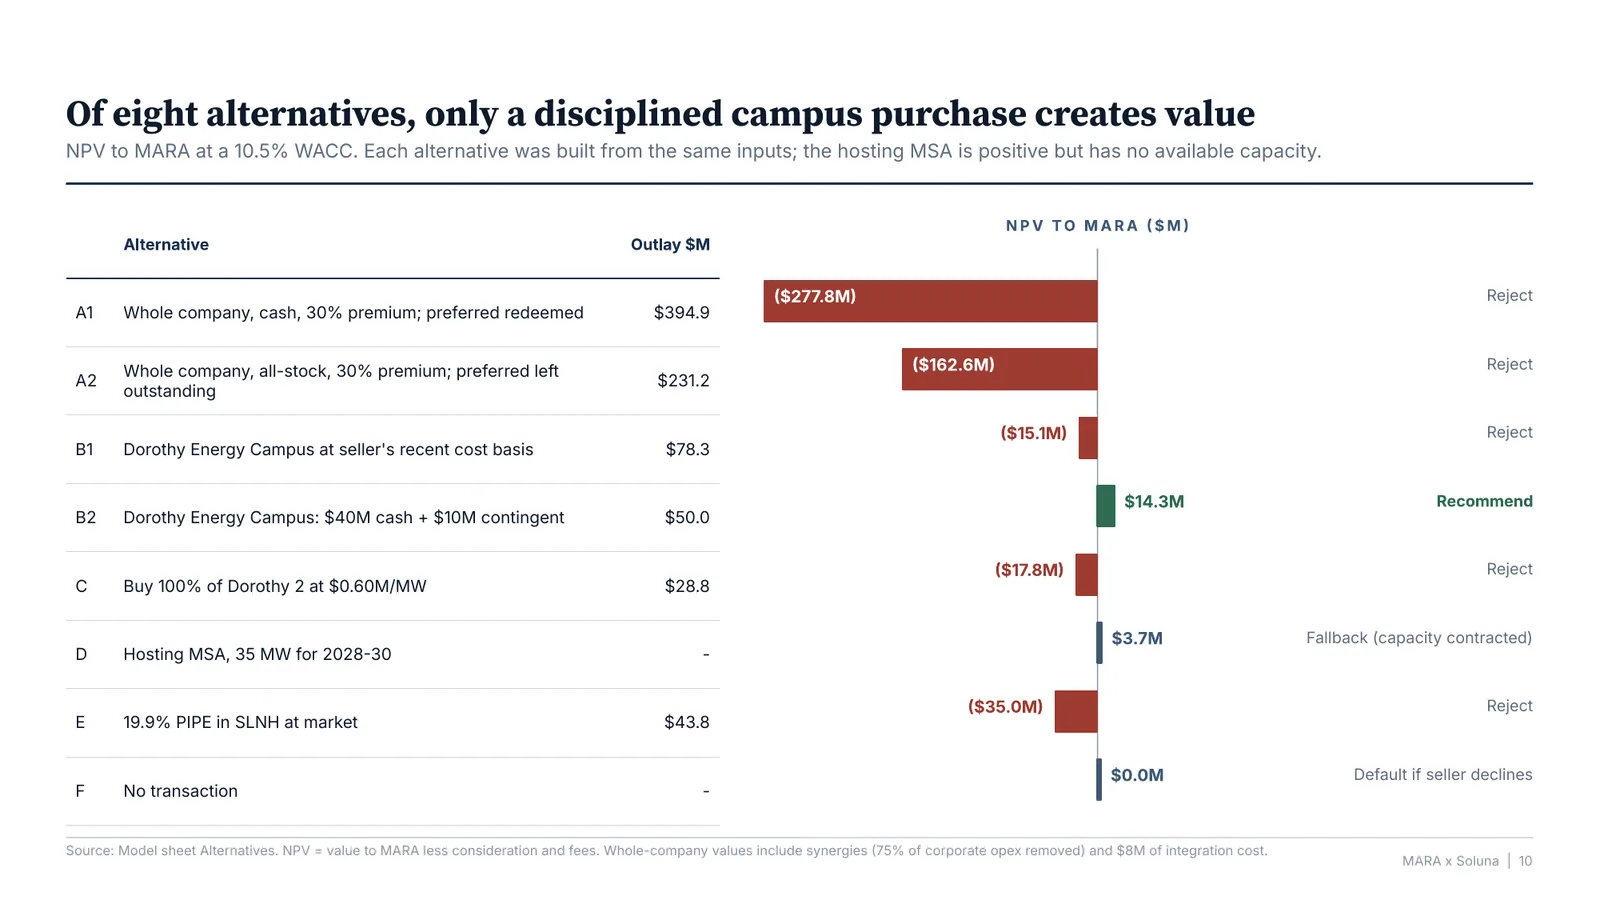
All alternatives use the same inputs. NPV to MARA is value less consideration and fees, at a 10.5% WACC. The whole-company cases include synergies (75% of corporate opex removed) and $8M of integration cost.
| Alternative | Outlay | NPV to MARA | Verdict | |
|---|---|---|---|---|
| A1 | Whole company, cash, 30% premium, preferred redeemed | $394.9M | ($277.8M) | Reject |
| A2 | Whole company, all-stock, 30% premium, preferred left outstanding | $231.2M | ($162.6M) | Reject |
| B1 | Dorothy Energy Campus at the seller’s recent cost basis | $78.3M | ($15.1M) | Reject |
| B2 | Dorothy Energy Campus: $40M cash + $10M contingent | $50.0M | +$14.3M | Recommend |
| C | Buy 100% of Dorothy 2 at $0.60M/MW | $28.8M | ($17.8M) | Reject |
| D | Hosting MSA, 35 MW for 2028-30 | - | +$3.7M | Fallback (capacity is contracted) |
| E | 19.9% PIPE in SLNH at market | $43.8M | ($35.0M) | Reject |
| F | No transaction | - | $0.0M | Default if seller declines |
- A1 is negative even at $0 per common share.
- A2 breaks even only at $0.29 per SLNH share. At the 30% premium it would issue 28.1M MARA shares, which is 6.8% of the pro forma company.
- C fails because Spring Lane’s Class B claims most of Dorothy 2’s cash.
6. The recommended structure
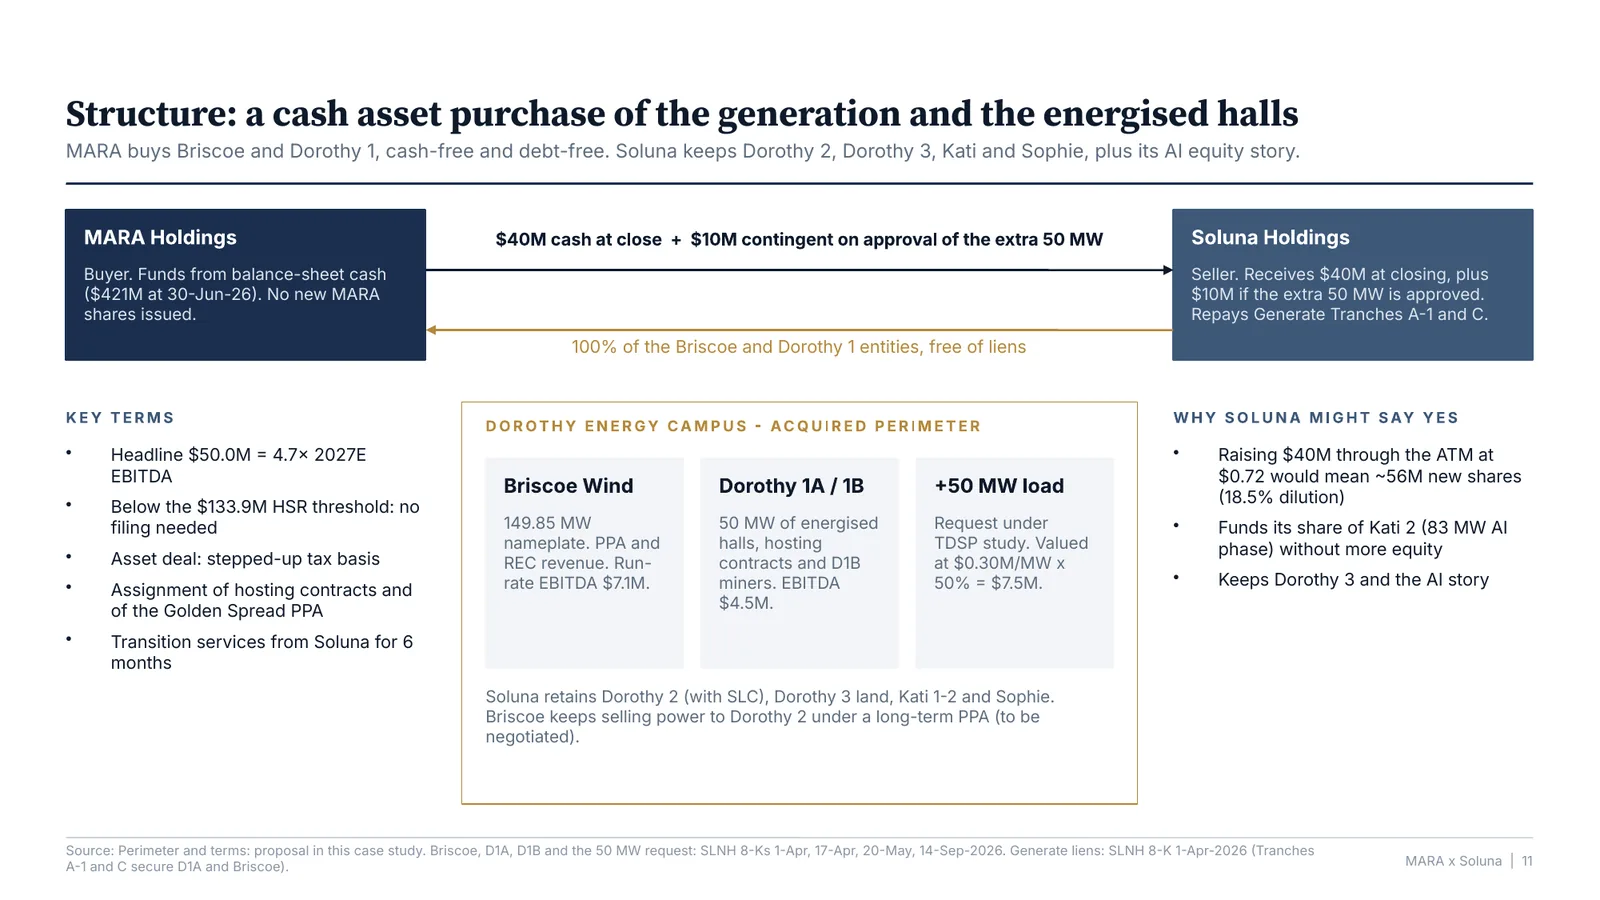
MARA buys 100% of the Briscoe and Dorothy 1 entities in a cash-free, debt-free asset purchase, funded from balance-sheet cash ($421M at 30-Jun-2026). No new MARA shares are issued. Soluna repays Generate Tranches A-1 and C, which secure Dorothy 1A and Briscoe, from the proceeds.
Perimeter
- Acquired: Briscoe Wind (149.85 MW nameplate, PPA and REC revenue, run-rate EBITDA $7.1M); Dorothy 1A/1B (50 MW of energised halls, the hosting contracts and the D1B miners; EBITDA $4.5M); and the 50 MW load request now under TDSP study (valued at $0.30M/MW x 50% probability = $7.5M).
- Retained by Soluna: Dorothy 2 (with Spring Lane), Dorothy 3 land, Kati 1-2 and Sophie. Briscoe keeps selling power to Dorothy 2 under a long-term PPA, to be negotiated.
Key terms
- The headline $50.0M is below the $133.9M HSR threshold, so no filing is needed.
- The asset deal gives MARA a stepped-up tax basis.
- The hosting contracts and the Golden Spread PPA are assigned to MARA.
- Soluna provides six months of transition services.
Why Soluna might say yes
- Raising $40M through its ATM at $0.72 would mean about 56M new shares (18.5% dilution).
- The proceeds fund its share of Kati 2 (the 83 MW AI phase) without more equity.
- It keeps Dorothy 3 and its AI story.
7. Campus DCF
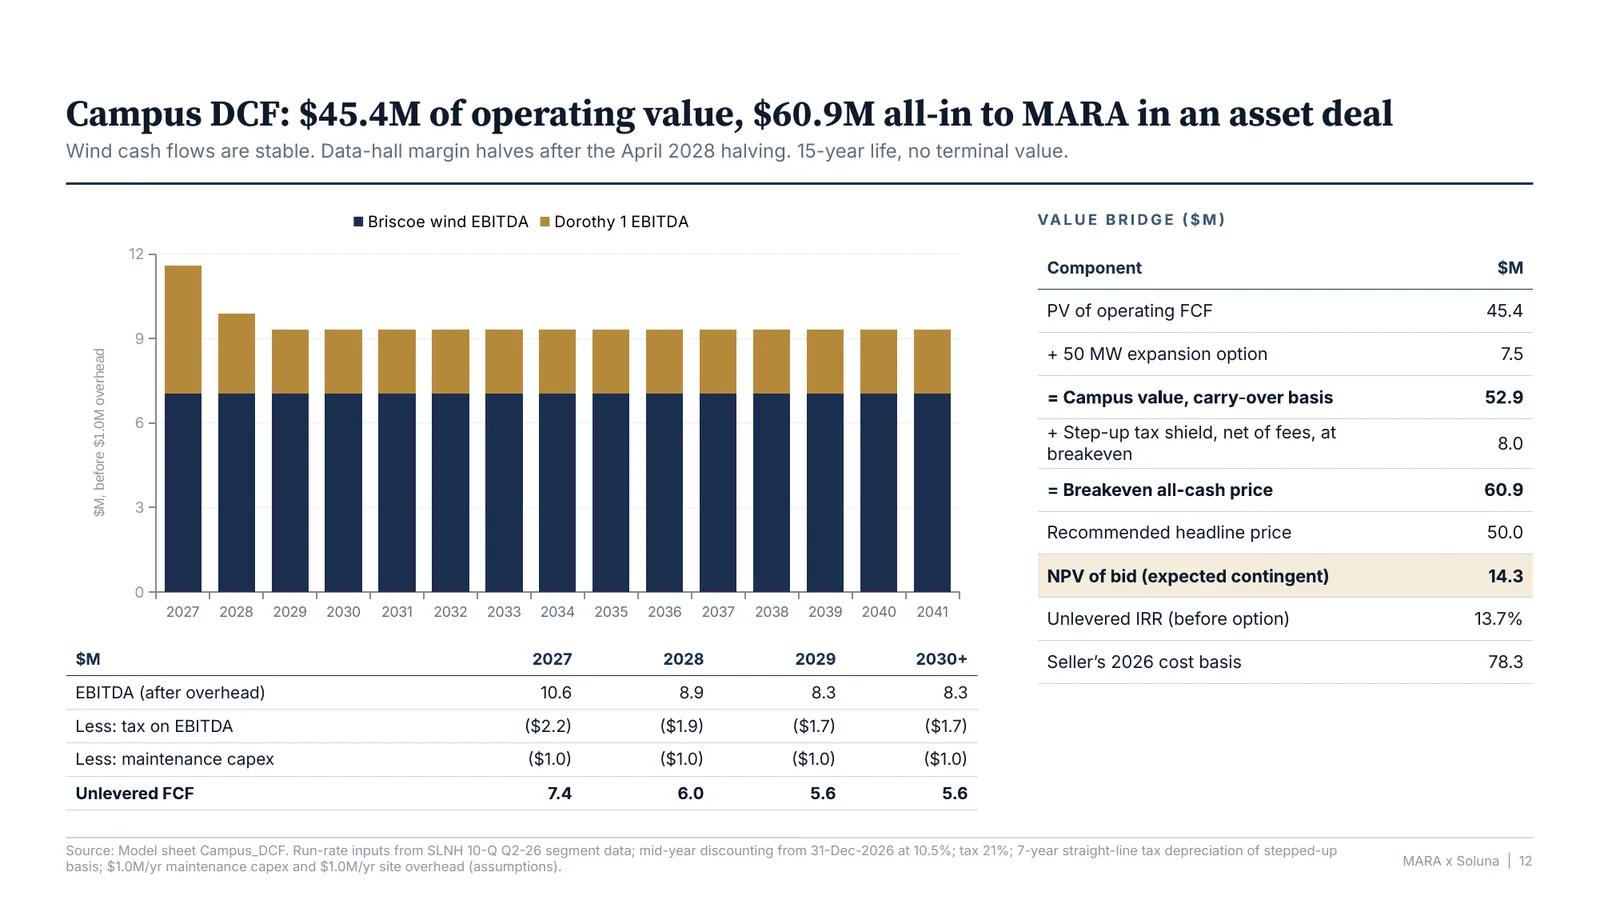
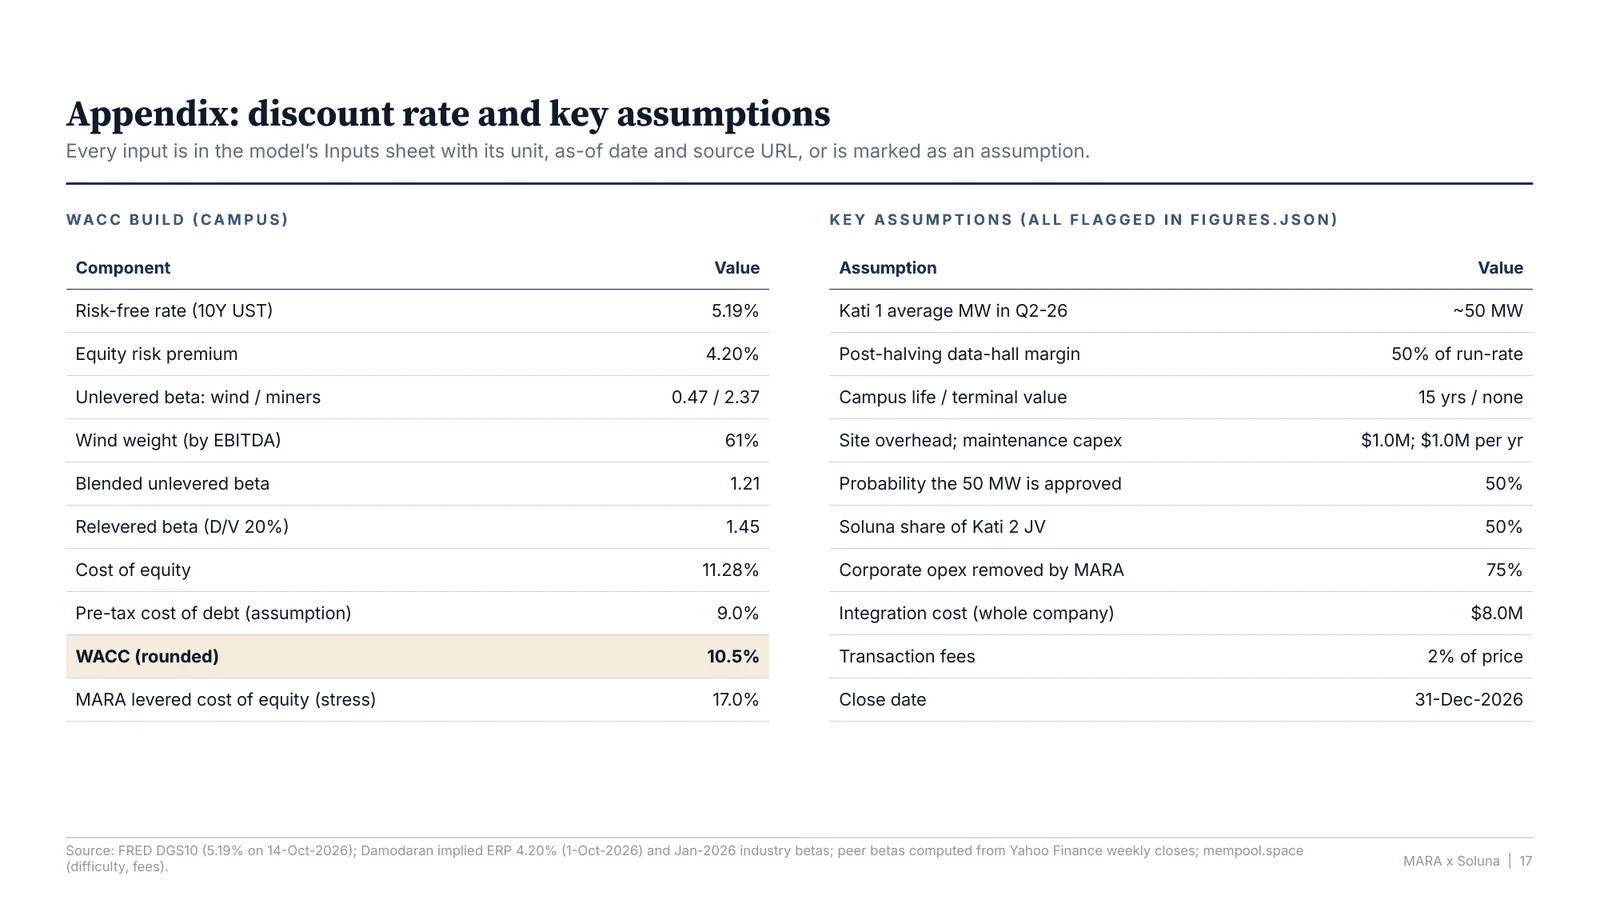
Assumptions: mid-year discounting from 31-Dec-2026 at 10.5%; 21% tax; 15-year life with no terminal value; $1.0M a year each of maintenance capex and site overhead. Data-hall margin falls to 50% of run-rate after the April 2028 halving.
| $M | 2027 | 2028 | 2029 | 2030+ |
|---|---|---|---|---|
| EBITDA (after overhead) | 10.6 | 8.9 | 8.3 | 8.3 |
| Less: tax on EBITDA | (2.2) | (1.9) | (1.7) | (1.7) |
| Less: maintenance capex | (1.0) | (1.0) | (1.0) | (1.0) |
| Unlevered FCF | 7.4 | 6.0 | 5.6 | 5.6 |
| Value bridge | $M |
|---|---|
| PV of operating FCF | 45.4 |
| + 50 MW expansion option | 7.5 |
| = Campus value, carry-over basis | 52.9 |
| + Step-up tax shield (7-year straight-line), net of fees, at breakeven | 8.0 |
| = Breakeven all-cash price (walk-away) | 60.9 |
| Recommended headline price | 50.0 |
| NPV of bid (contingent at expected value) | 14.3 |
Discount rate.
- The cost of equity is 11.28%: rf 5.19% (10Y UST, 14-Oct-2026) + relevered beta 1.45 x ERP 4.20% (Damodaran implied, 1-Oct-2026).
- The beta is a blend of wind (unlevered 0.47, Damodaran) and the miners’ peer median (2.37, computed from 102 weekly returns). The blend is weighted by EBITDA (wind 61%), giving an unlevered beta of 1.21, relevered at 20% D/V.
- With a 9.0% pre-tax cost of debt, the WACC is 10.45%, rounded to 10.5%.
- v1 used about 20%, which was right for a pure miner; the campus is now mostly wind cash flow.
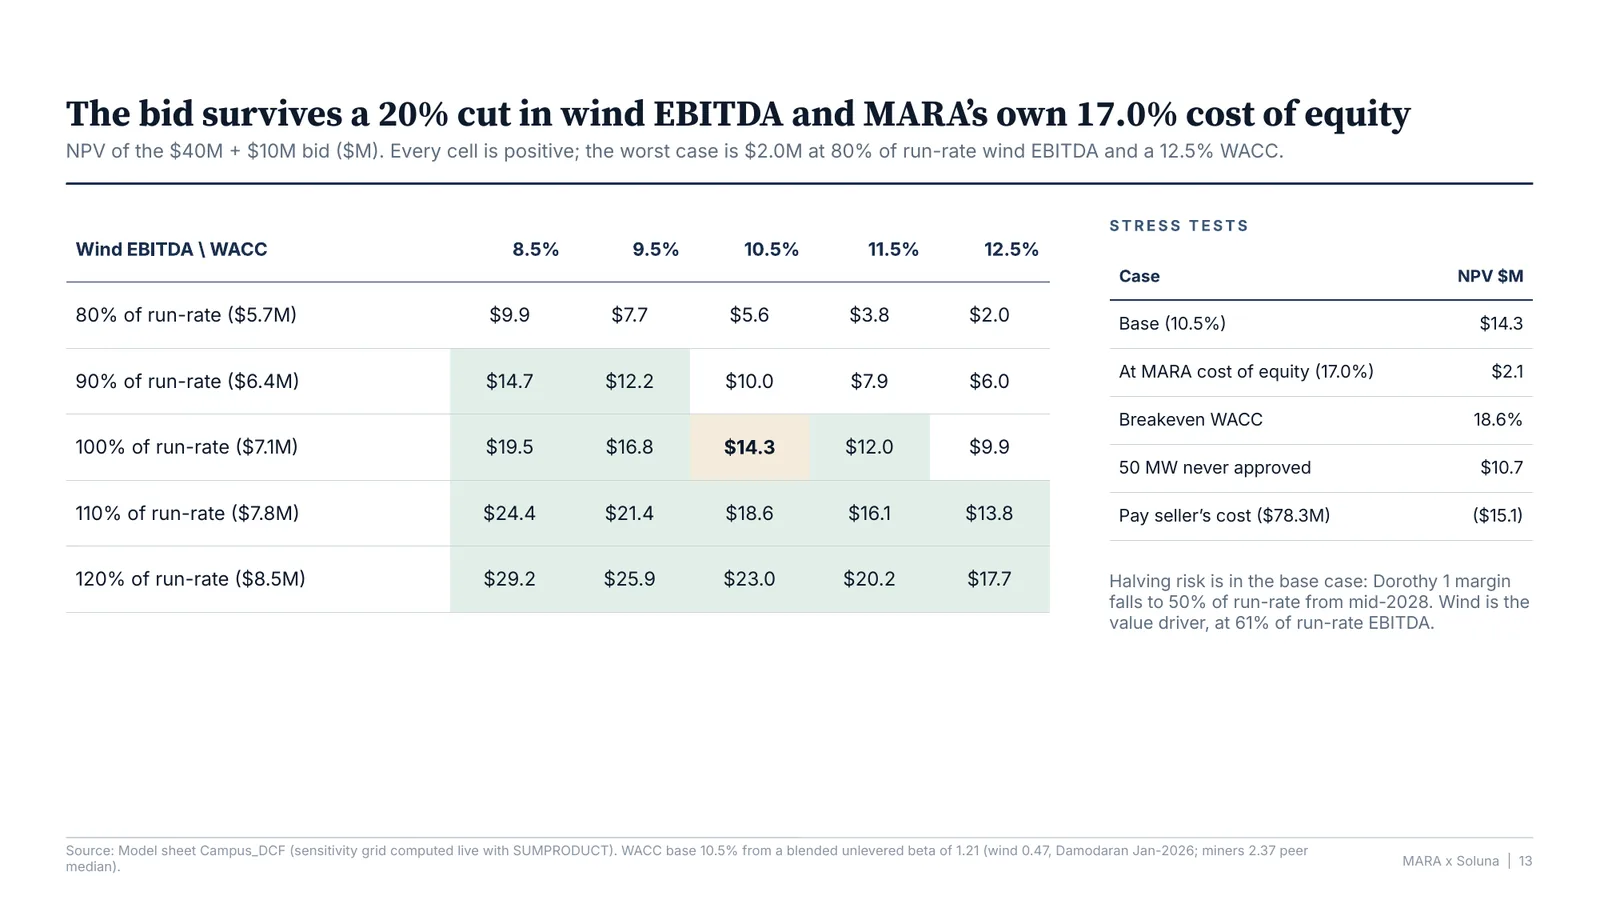
Sensitivity: NPV of the bid ($M)
| Wind EBITDA \ WACC | 8.5% | 9.5% | 10.5% | 11.5% | 12.5% |
|---|---|---|---|---|---|
| 80% ($5.7M) | 9.9 | 7.7 | 5.6 | 3.8 | 2.0 |
| 90% ($6.4M) | 14.7 | 12.2 | 10.0 | 7.9 | 6.0 |
| 100% ($7.1M) | 19.5 | 16.8 | 14.3 | 12.0 | 9.9 |
| 110% ($7.8M) | 24.4 | 21.4 | 18.6 | 16.1 | 13.8 |
| 120% ($8.5M) | 29.2 | 25.9 | 23.0 | 20.2 | 17.7 |
Every cell is positive.
Stress tests
- At MARA’s own 17.0% cost of equity, NPV is +$2.1M.
- The breakeven WACC is 18.6%.
- If the 50 MW is never approved, MARA pays no contingent and NPV is +$10.7M.
- Paying the seller’s $78.3M cost basis gives ($15.1M).
8. Effects on MARA
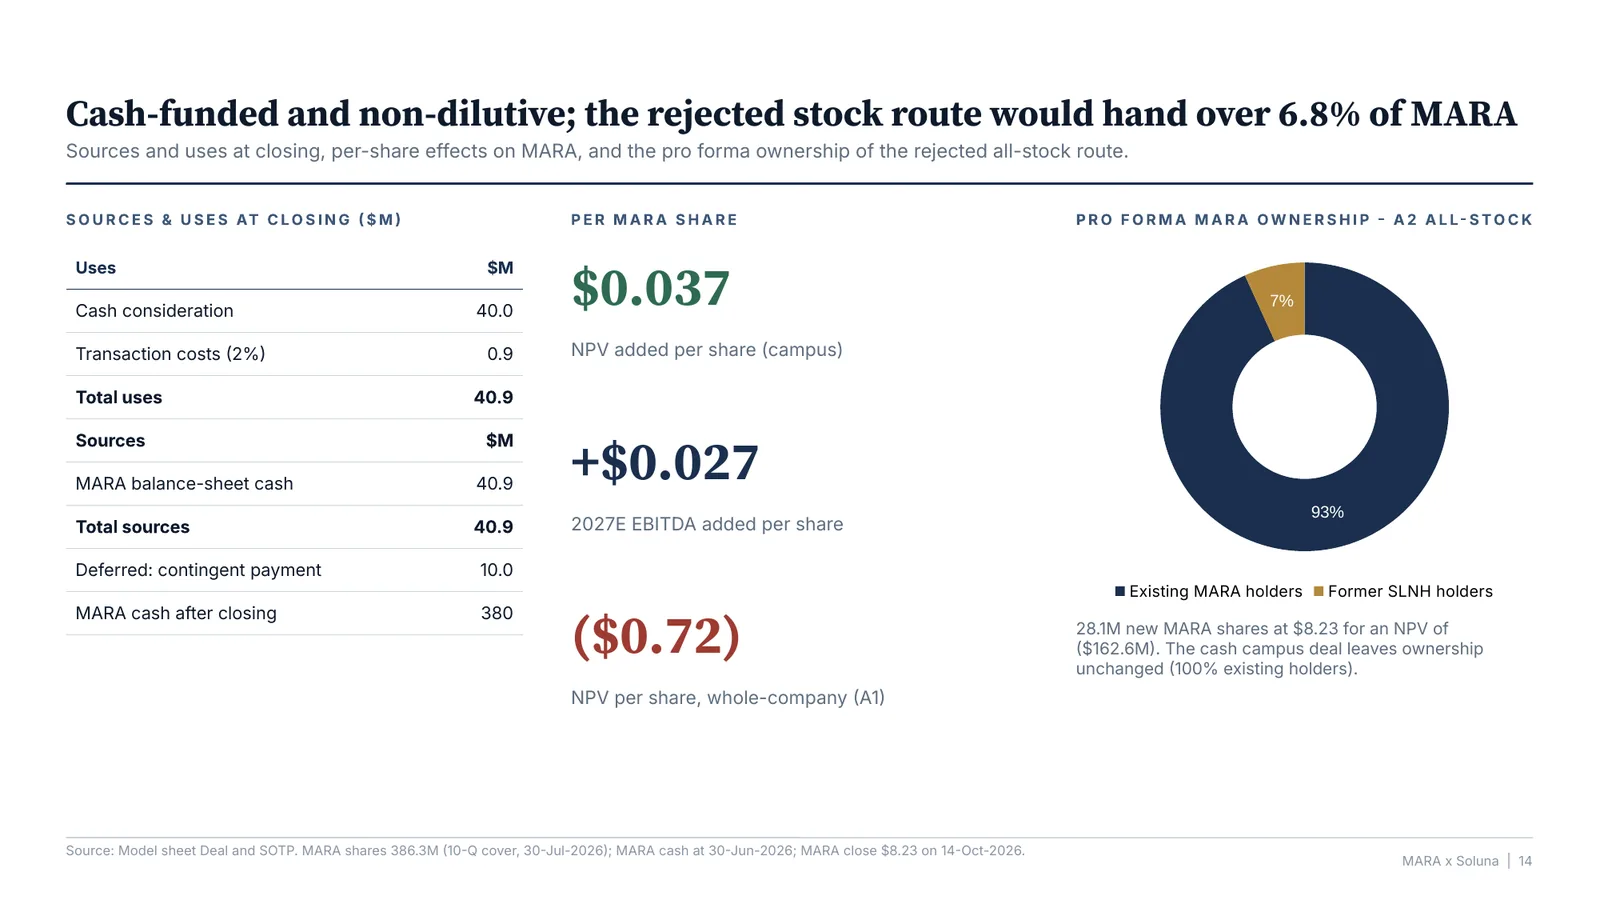
Sources and uses. MARA uses $40.9M of balance-sheet cash at closing: $40.0M of consideration plus $0.9M of fees. The $10.0M contingent payment is deferred. MARA’s cash after closing is about $380M.
Per MARA share (386.3M shares)
- The campus deal adds $0.037 of NPV and $0.027 of 2027E EBITDA.
- By contrast, the whole-company cash bid (A1) would destroy $0.72 per share.
Ownership. The cash deal leaves MARA’s ownership unchanged. The rejected all-stock route (A2) would hand 6.8% of MARA to former SLNH holders.
9. Risks and mitigants
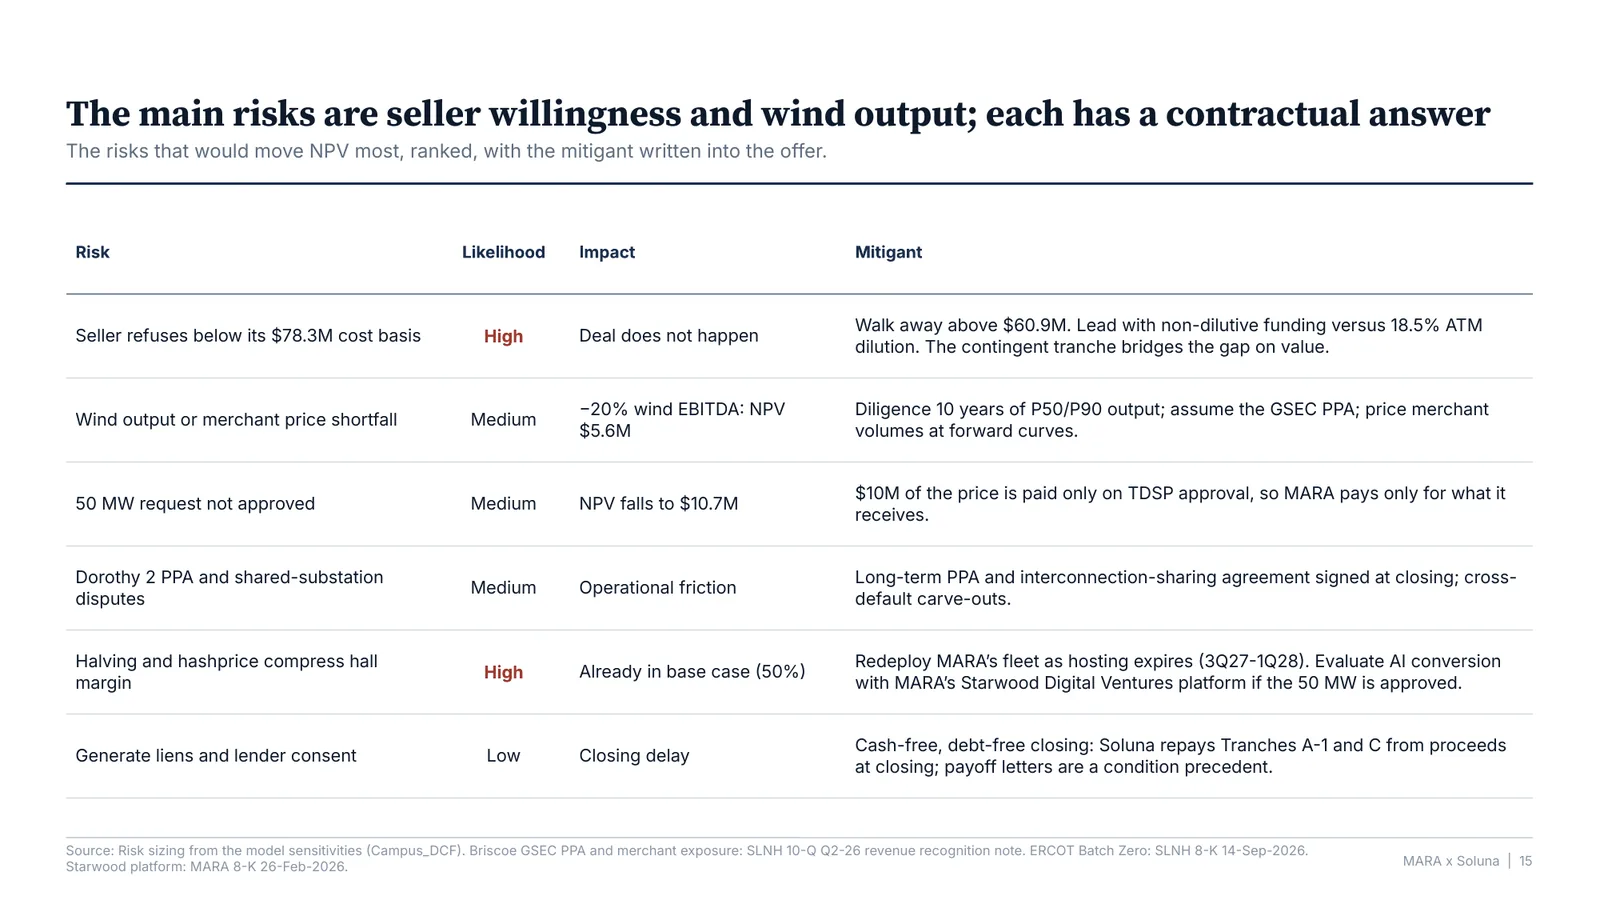
| Risk | Likelihood | Impact | Mitigant |
|---|---|---|---|
| Seller refuses below its $78.3M cost basis | High | Deal does not happen | Walk away above $60.9M. Lead with non-dilutive funding versus 18.5% ATM dilution. The contingent tranche bridges the gap on value. |
| Wind output or merchant price shortfall | Medium | -20% wind EBITDA: NPV $5.6M | Diligence 10 years of P50/P90 output; assume the GSEC PPA; price merchant volumes at forward curves. |
| 50 MW request not approved | Medium | NPV falls to $10.7M | $10M of the price is paid only on TDSP approval. |
| Dorothy 2 PPA and shared-substation disputes | Medium | Operational friction | Long-term PPA and interconnection-sharing agreement signed at closing; cross-default carve-outs. |
| Halving and hashprice compress hall margin | High | Already in base case (50%) | Redeploy MARA’s fleet as hosting expires (3Q27-1Q28); evaluate AI conversion with MARA’s Starwood Digital Ventures platform if the 50 MW is approved. |
| Generate liens and lender consent | Low | Closing delay | Soluna repays Tranches A-1 and C at closing; payoff letters are a condition precedent. |
10. Process and decision rules
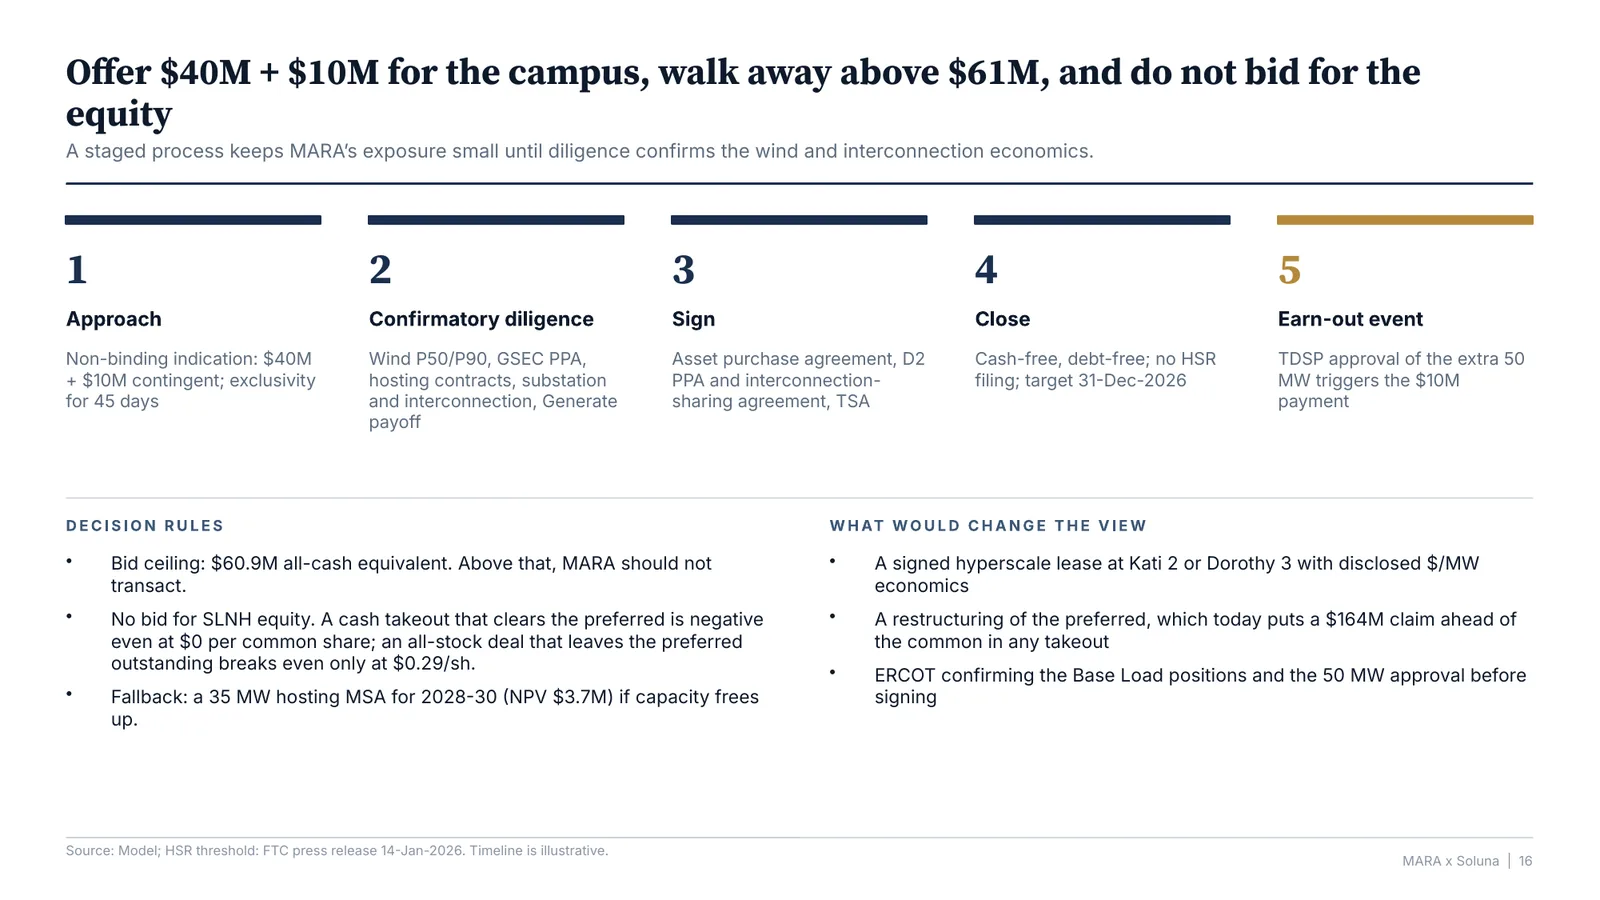
Process. The timeline is illustrative.
- Approach: non-binding indication of $40M + $10M contingent, with 45 days of exclusivity.
- Confirmatory diligence: wind P50/P90, the GSEC PPA, the hosting contracts, the substation and interconnection, and the Generate payoff.
- Sign: the asset purchase agreement, the D2 PPA and interconnection-sharing agreement, and the TSA.
- Close: cash-free and debt-free, with no HSR filing; target 31-Dec-2026.
- Contingent payment: TDSP approval of the extra 50 MW triggers the $10M.
Decision rules
- Bid ceiling: $60.9M all-cash equivalent.
- No bid for SLNH equity. A cash takeout that clears the preferred is negative even at $0 per common share. An all-stock deal that leaves the preferred outstanding breaks even only at $0.29 per share.
- Fallback: a 35 MW hosting MSA for 2028-30 (NPV +$3.7M) if capacity frees up.
What would change the view
- A signed hyperscale lease at Kati 2 or Dorothy 3 with disclosed $/MW economics.
- A restructuring of the preferred, which today puts a $164M claim ahead of the common in any takeout.
- ERCOT confirming the Base Load positions, and the 50 MW approval arriving before signing.
Limitations and items not verified
- Not verified from filings:
- Warrant strike prices.
- Series A change-of-control redemption mechanics.
- Briscoe vintage, remaining life and P50 output.
- Assignability of the Dorothy 2 PPA.
- Metrobloks JV economics (assumed 50%).
- Whether MARA’s earlier Sophie co-location is still current.
- Long Ridge closing status after the 6-Aug-2026 10-Q.
- Estimated: Kati 1’s Q2-26 average load (about 50 MW) is an assumption.
- Data timing: IREN’s share count is dated 30-Apr. The Damodaran industry-beta file is the January 2026 update.
- Model conventions: synergy, approval-probability and post-halving margin figures are assumptions, flagged in
figures.json.