Independent M&A and merger-arbitrage case study · Public information only
Union Pacific / Norfolk Southern: the first transcontinental railroad
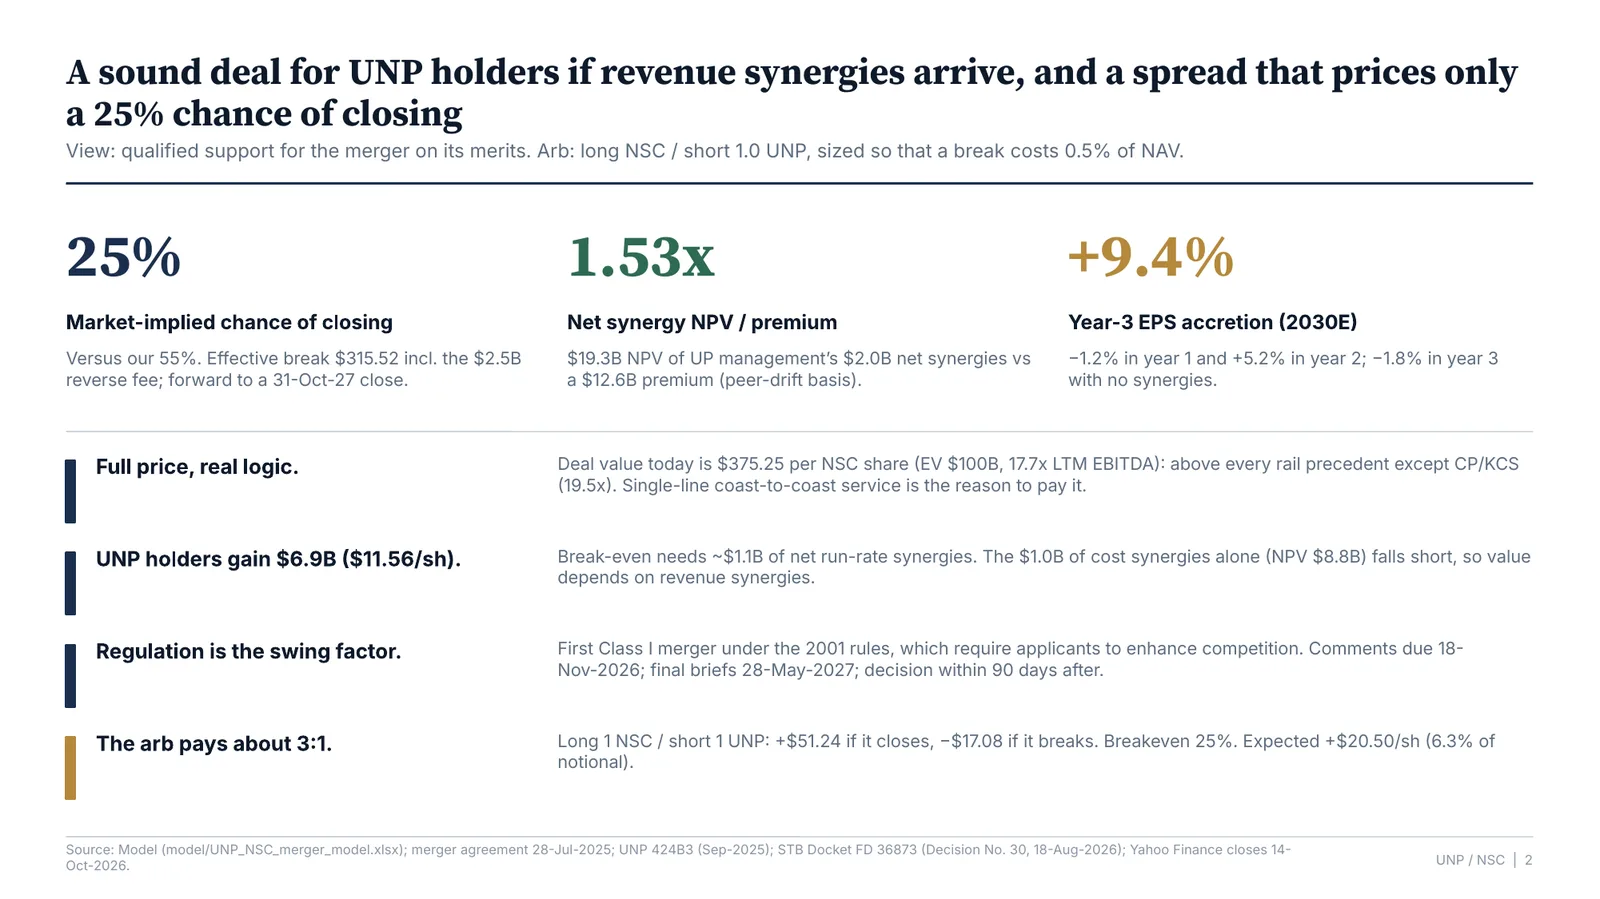
UNP is paying a full price: $375.25 per NSC share, 17.7x LTM EBITDA and 21% above NSC's standalone DCF. But $19.3B of net synergies cover the $12.6B premium 1.53x, so UNP holders gain $6.9B. The STB review is the swing factor: the $51.52 spread (15.9%) implies a 25% chance of closing against our 55%.
Recommendation
Long NSC / short 1.0 UNP at 9.5% NAV
Qualified support on deal merit · break costs 0.5% NAV
Synergies vs. premium
1.53x
$19.3B net vs $12.6B · UNP holders +$6.9B
P(close): mkt vs. ours
25% vs 55%
STB review is the swing factor
Spread
$51.52
15.9% to $375.25 per NSC share
Not prepared for, reviewed by, or affiliated with Union Pacific, Norfolk Southern, their advisors, or any employer or client. Not investment advice. All figures in US$.
Recommendation
Deal merit: qualified support for UNP shareholders. Arb: long NSC / short 1.0 UNP, sized at 9.5% of NAV long notional so that a break costs 0.5% of NAV.
- The price is full, but the synergies pay for it. Today the consideration is worth $375.25 per NSC share: an enterprise value of $100.1B, or 17.7x LTM EBITDA. UP management’s $2.0B net synergy case is worth $19.3B against a $12.6B premium (1.53x cover).
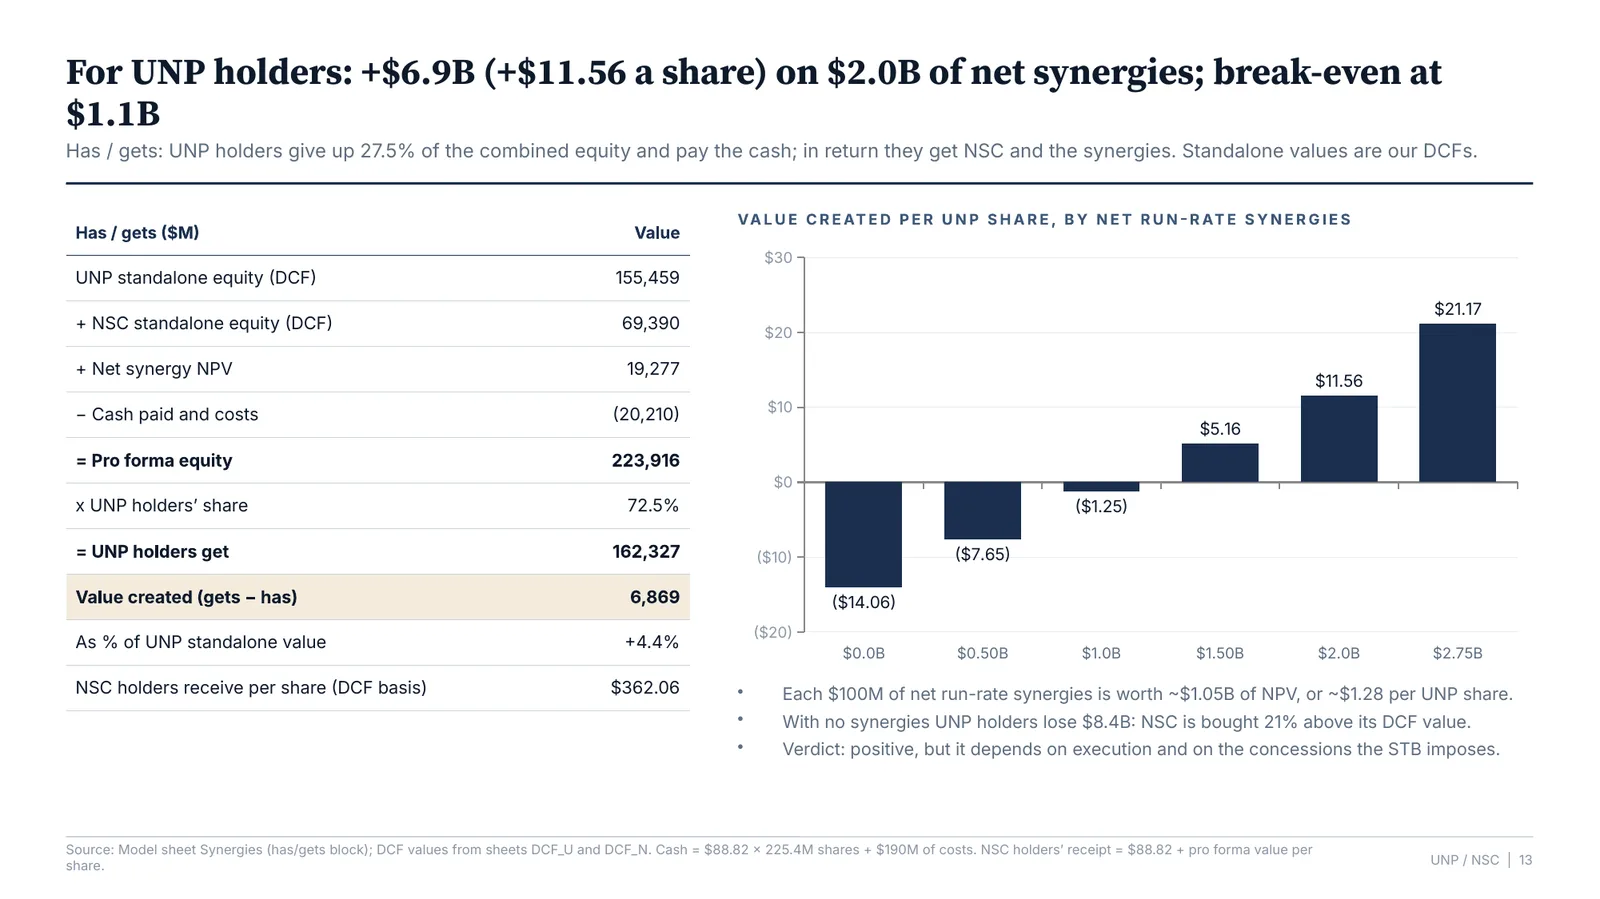
- UNP holders gain $6.9B ($11.56 a share, +4.4%) in a has/gets analysis. Break-even is about $1.1B of net run-rate synergies. The $1.0B of cost synergies alone does not get there.
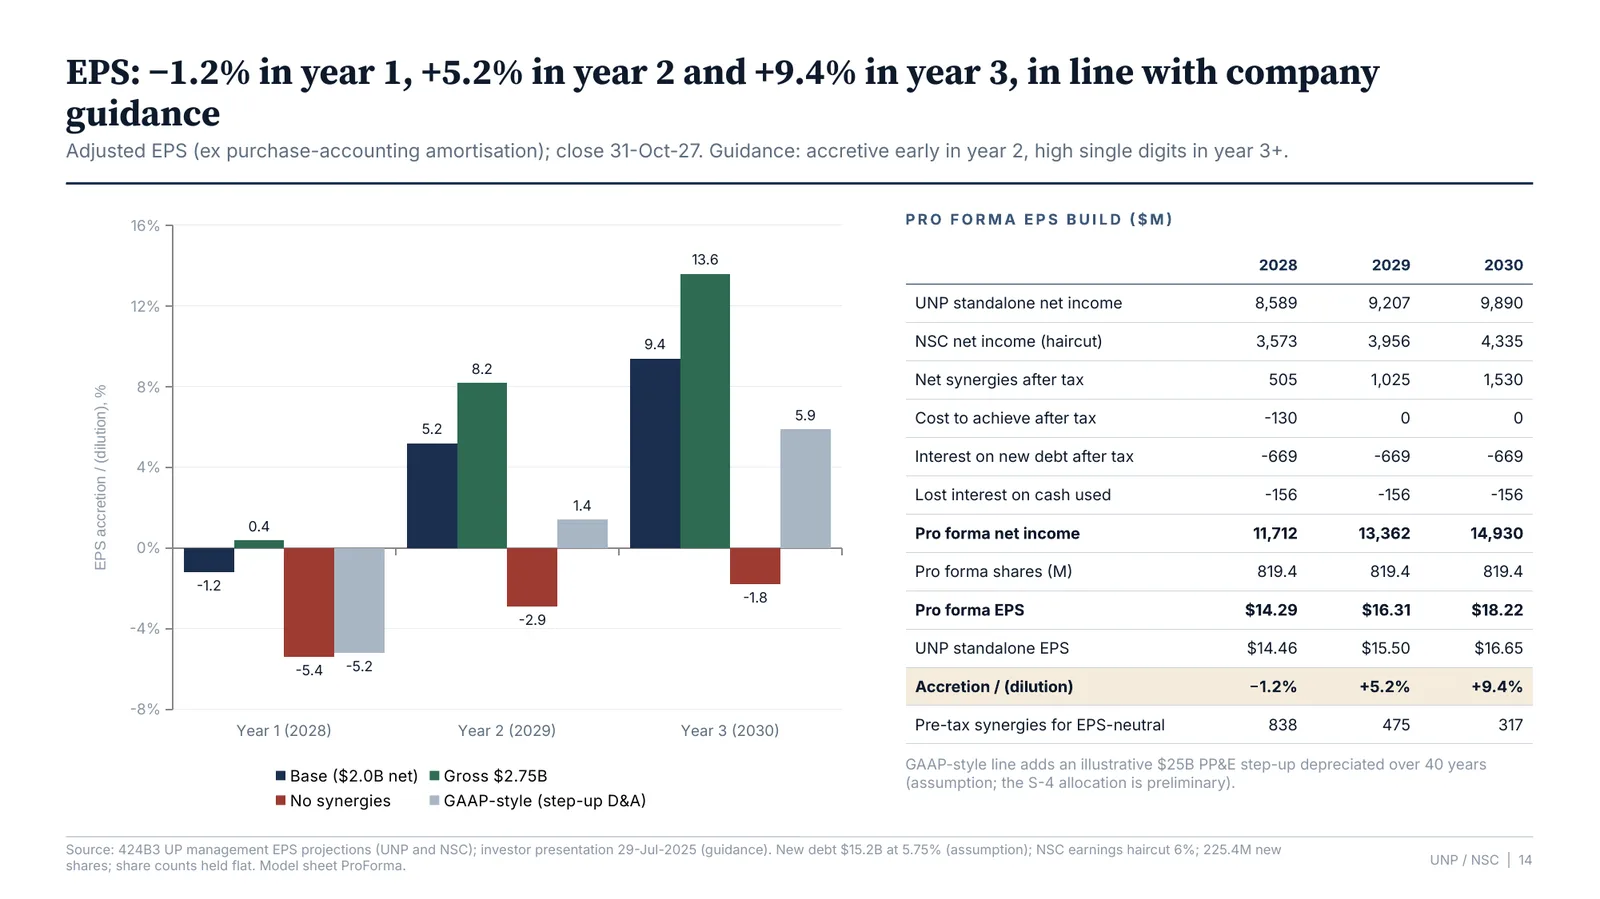
- EPS is -1.2% / +5.2% / +9.4% in years 1-3, in line with guidance. Leverage peaks at ~3.1x (2027E) and falls to ~2.4x by the end of year 2 before buybacks.
- The market implies only a 25% chance of closing, against our 55%. Long NSC / short 1.0 UNP makes $51.24 per NSC share if the deal closes and loses $17.08 if it breaks (3.0:1). It breaks even at 25%; at 55% the expected gain is $20.50 (6.3% of notional).
1. The deal
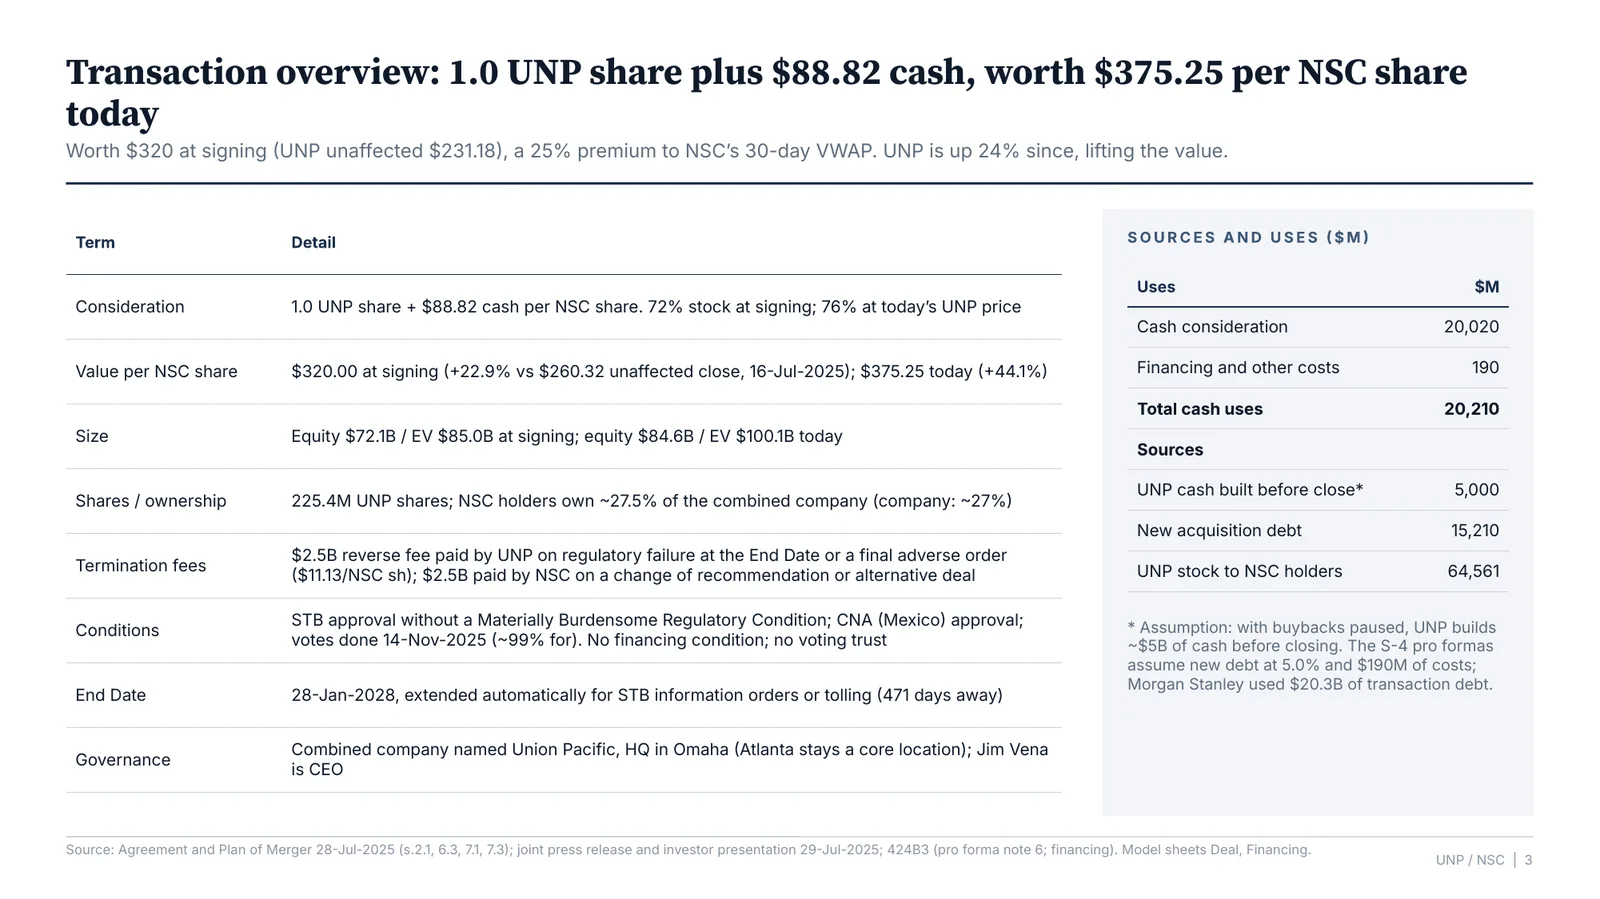
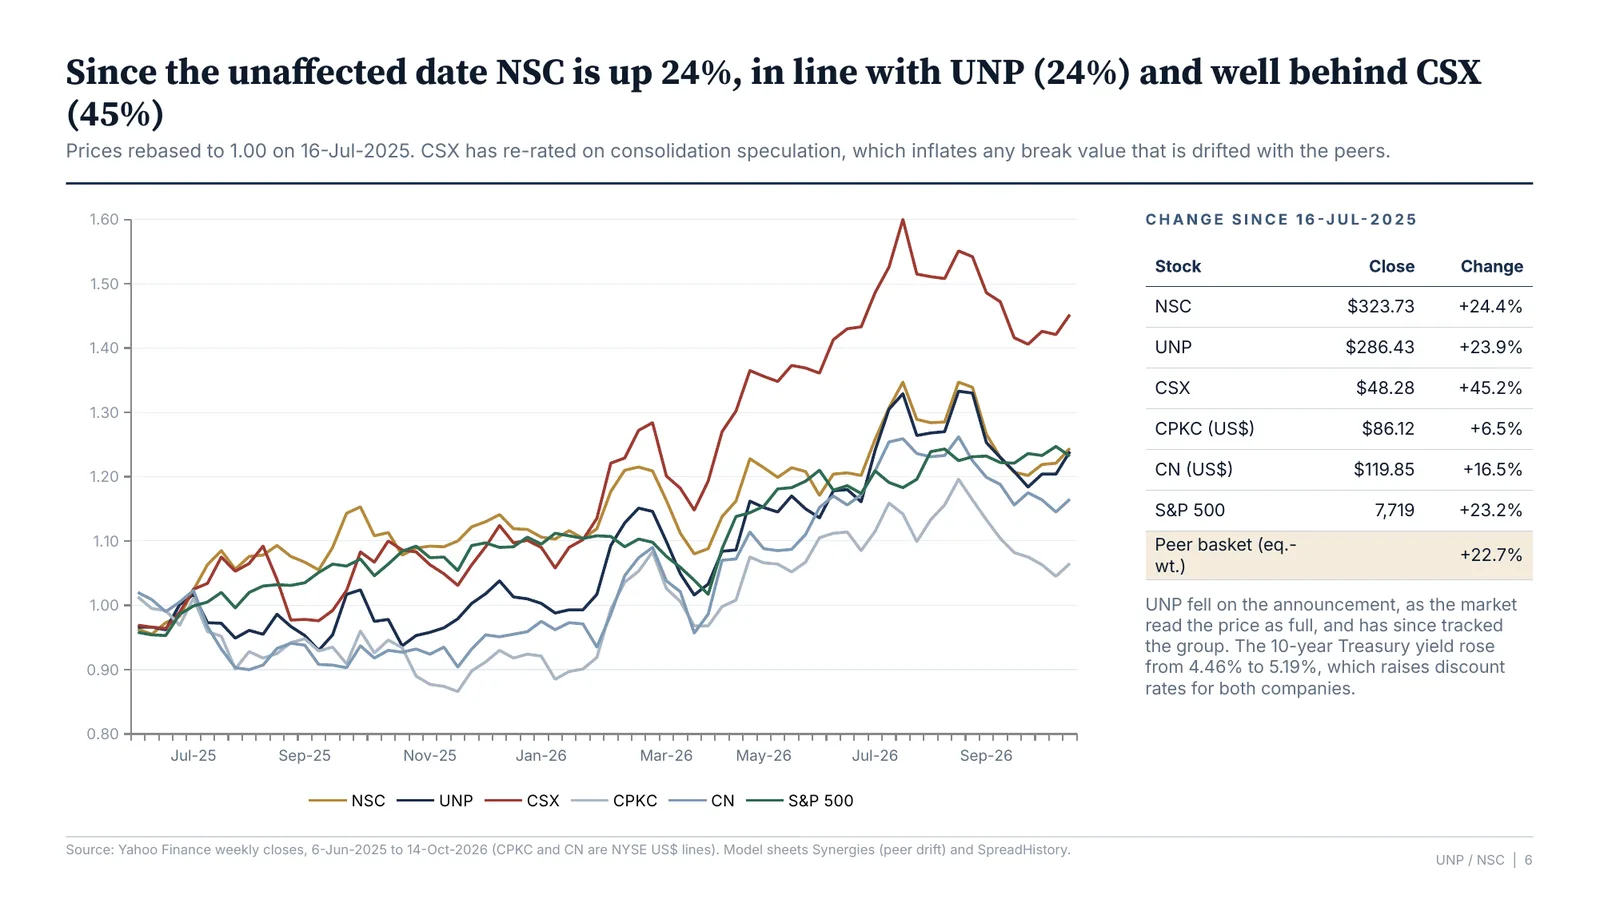
On 29-Jul-2025 Union Pacific agreed to buy Norfolk Southern for 1.0 UNP share plus $88.82 in cash per NSC share. At UNP’s $231.18 unaffected close (16-Jul-2025) that was $320.00, a 22.9% premium to NSC’s $260.32 unaffected close and a 25% premium to its 30-day VWAP, for an equity value of $72.1B and an EV of about $85B. UNP has since risen to $286.43, so the offer is now worth $375.25 (+44.1% over the unaffected price).
| Term | Detail |
|---|---|
| Consideration | 1.0 UNP + $88.82 cash; 72% stock at signing, 76% today; fixed ratio, no collar |
| Shares and ownership | 225.4M UNP shares; NSC holders own ~27.5% (company: ~27%) |
| Reverse termination fee | $2.5B ($11.13/NSC share), paid by UNP if the End Date passes without STB approval or a final order blocks the deal |
| NSC termination fee | $2.5B on a change of recommendation or an alternative deal |
| Conditions | STB approval without a Materially Burdensome Regulatory Condition; Mexican antitrust approval; votes passed 14-Nov-2025 (~99% for). No financing condition, no voting trust |
| End Date | 28-Jan-2028, extended automatically for STB information orders or tolling |
| Financing | ~$20.0B of cash consideration; we assume ~$5B of pre-close cash and $15.2B of new debt |
2. Why do it: the first single-line coast-to-coast railroad
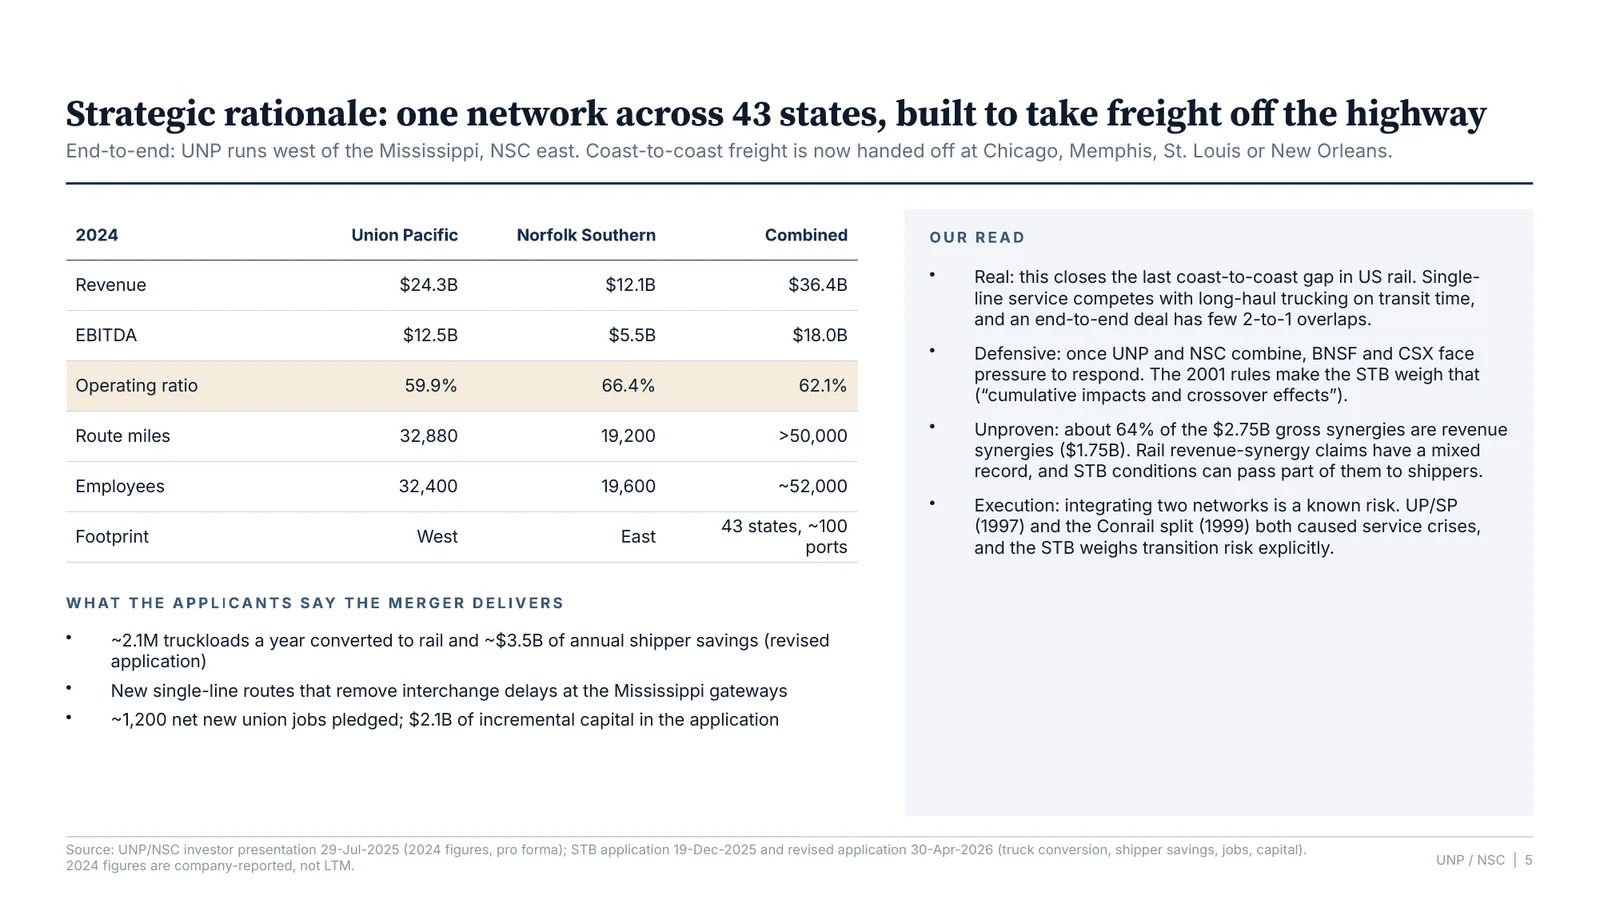
UNP runs west of the Mississippi and NSC east of it. Today coast-to-coast freight changes hands at Chicago, Memphis, St. Louis or New Orleans. Combined, the companies would have $36.4B of 2024 revenue, $18.0B of EBITDA, a 62.1% operating ratio and more than 50,000 route miles in 43 states. The applicants claim ~2.1M truckloads a year converted to rail and ~$3.5B of annual shipper savings.
Our read: the logic is real and the overlaps are few, but about 64% of the $2.75B gross synergies are revenue synergies, which have a mixed record in rail and can be partly handed to shippers through STB conditions. UP/SP and the Conrail split are reminders that integration can go badly.
3. Standalone value: the deal pays 21% over NSC's DCF
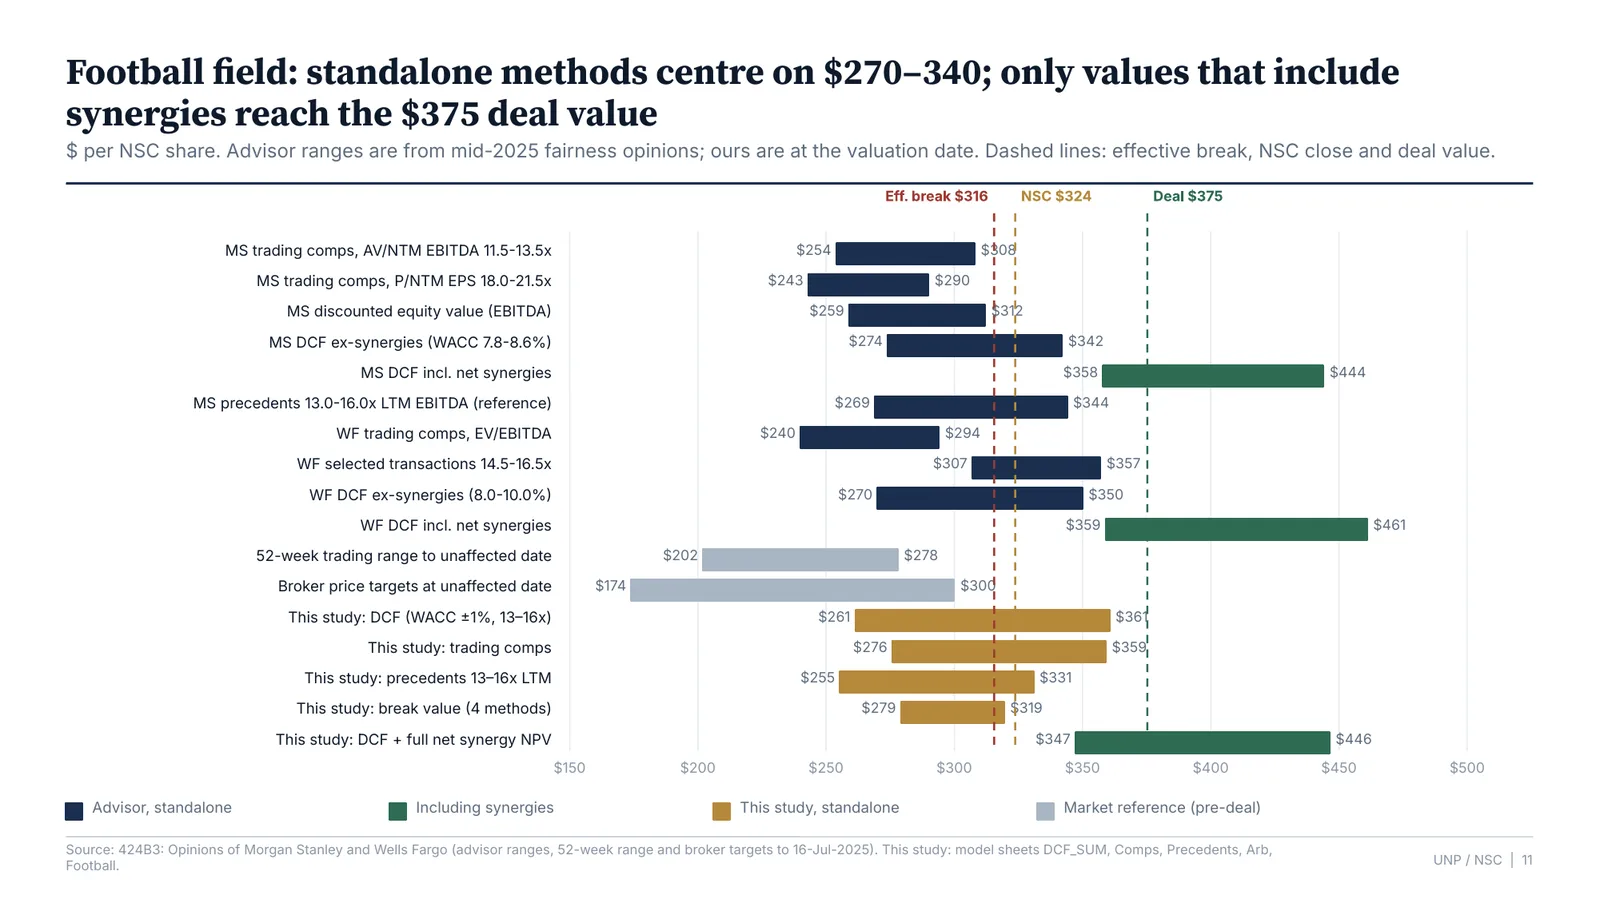
| Method | NSC $/share |
|---|---|
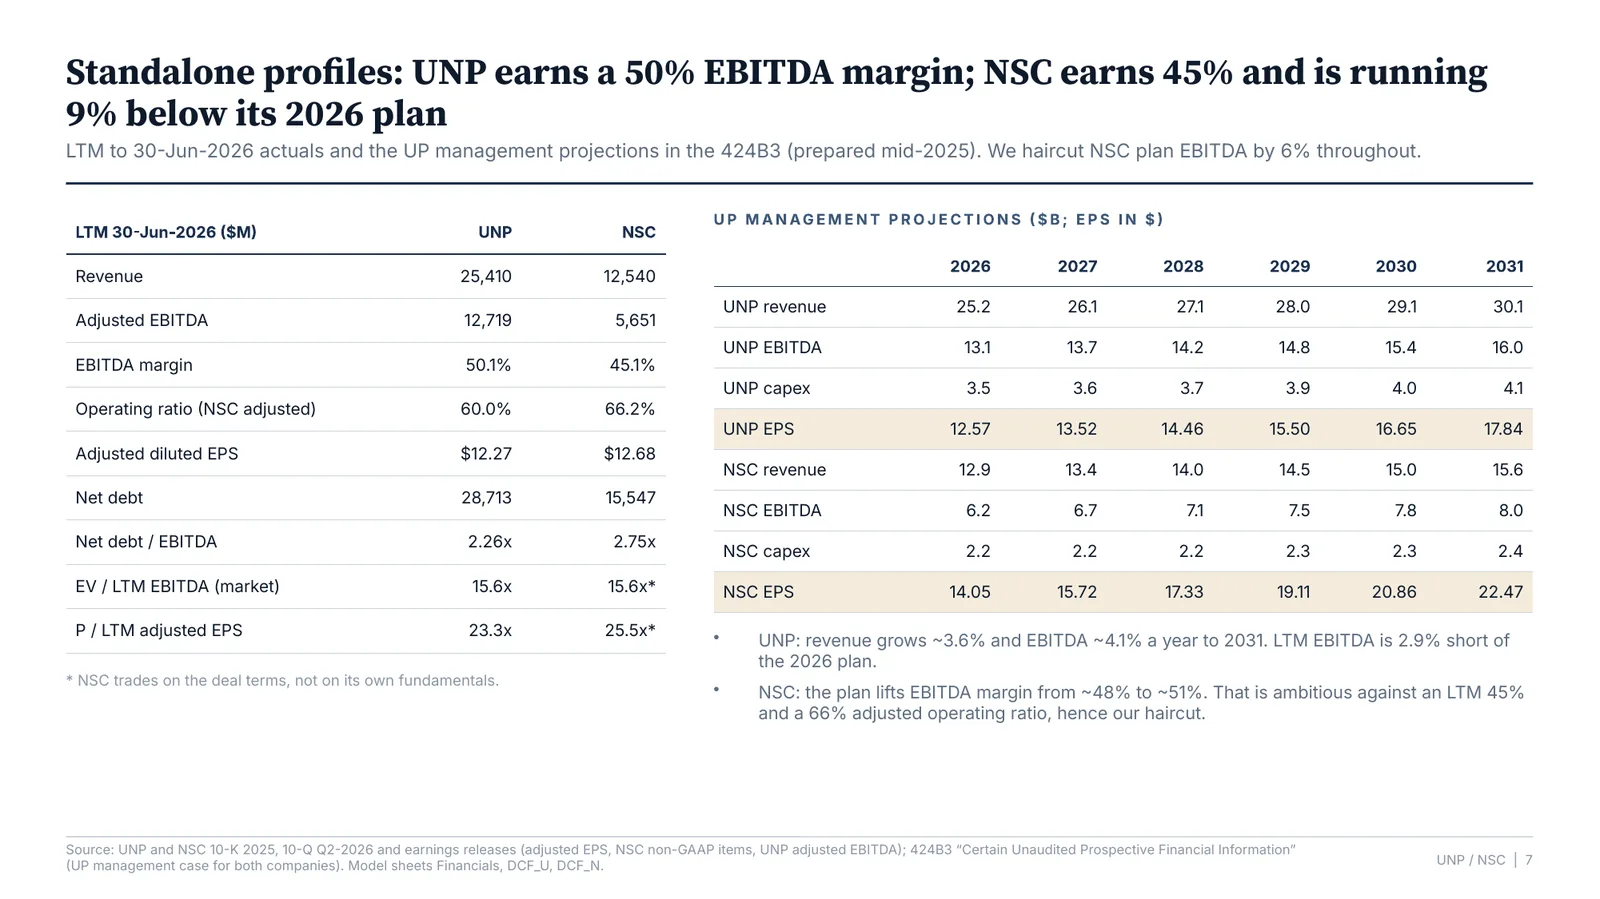
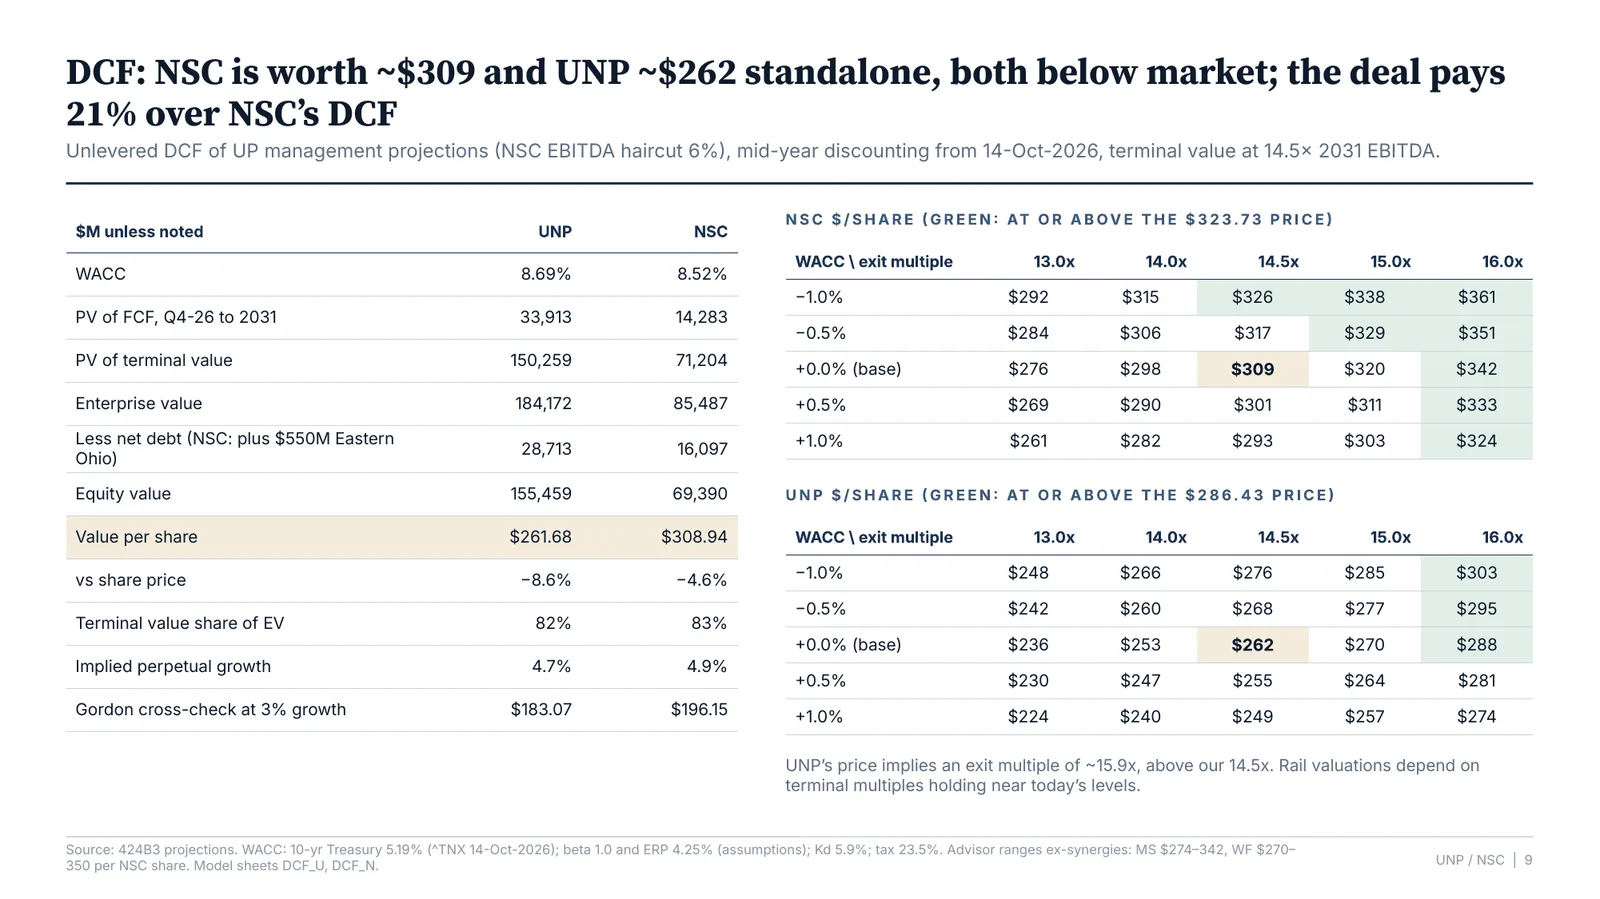
| DCF (WACC 8.52%, 14.5x exit; NSC plan EBITDA haircut 6%) | $308.94 |
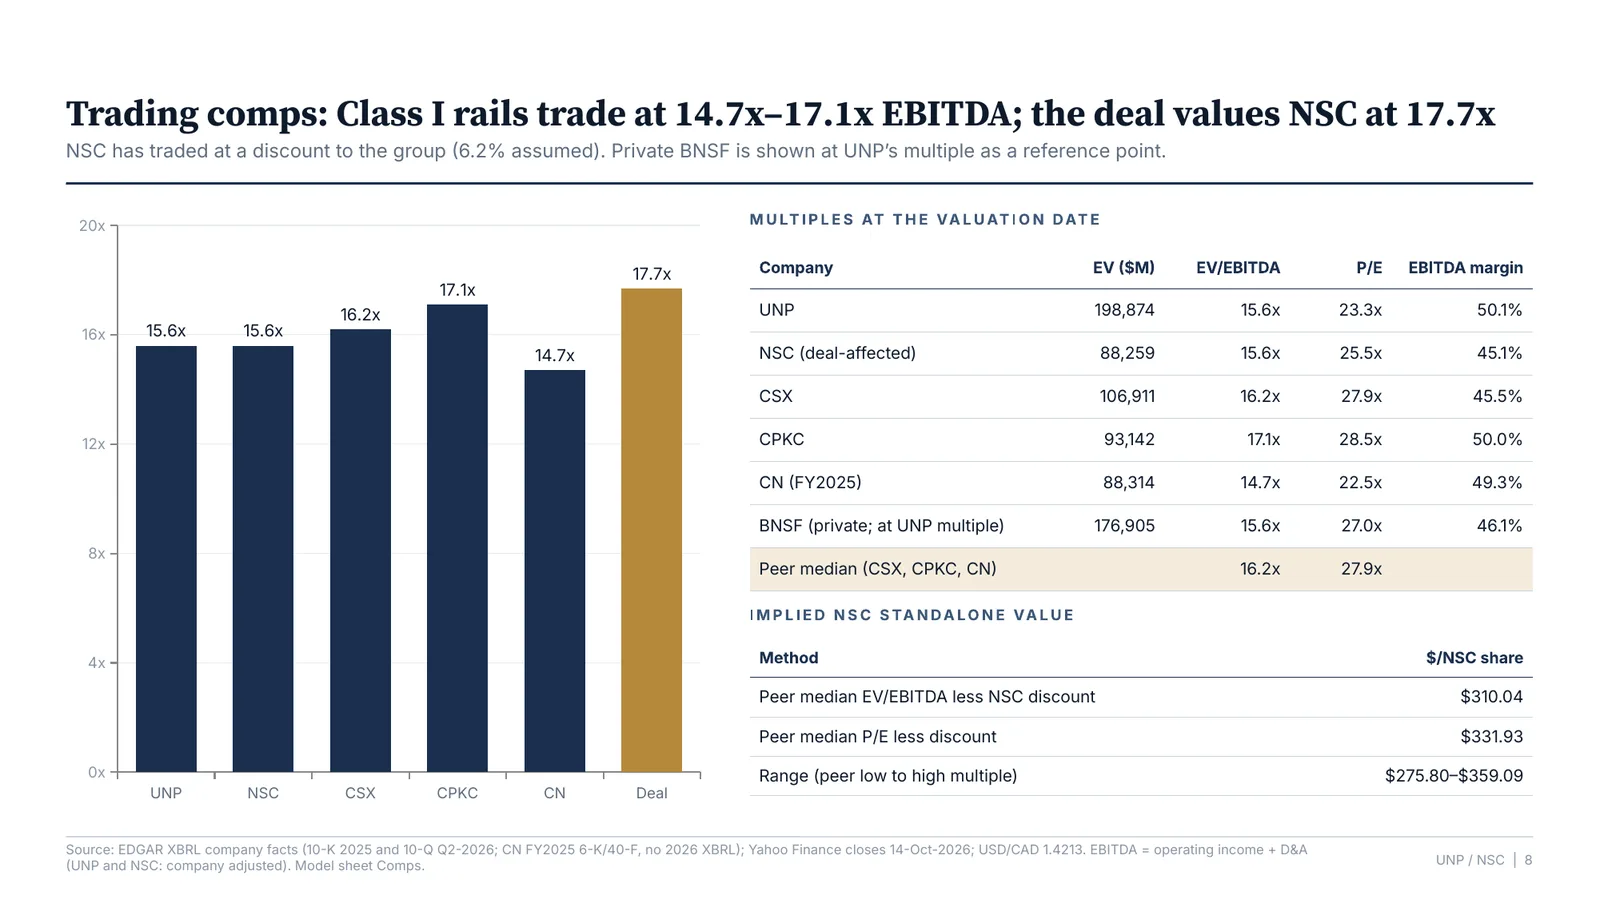
| Trading comps: peer median 16.2x EV/EBITDA less a 6.2% NSC discount | $310.04 |
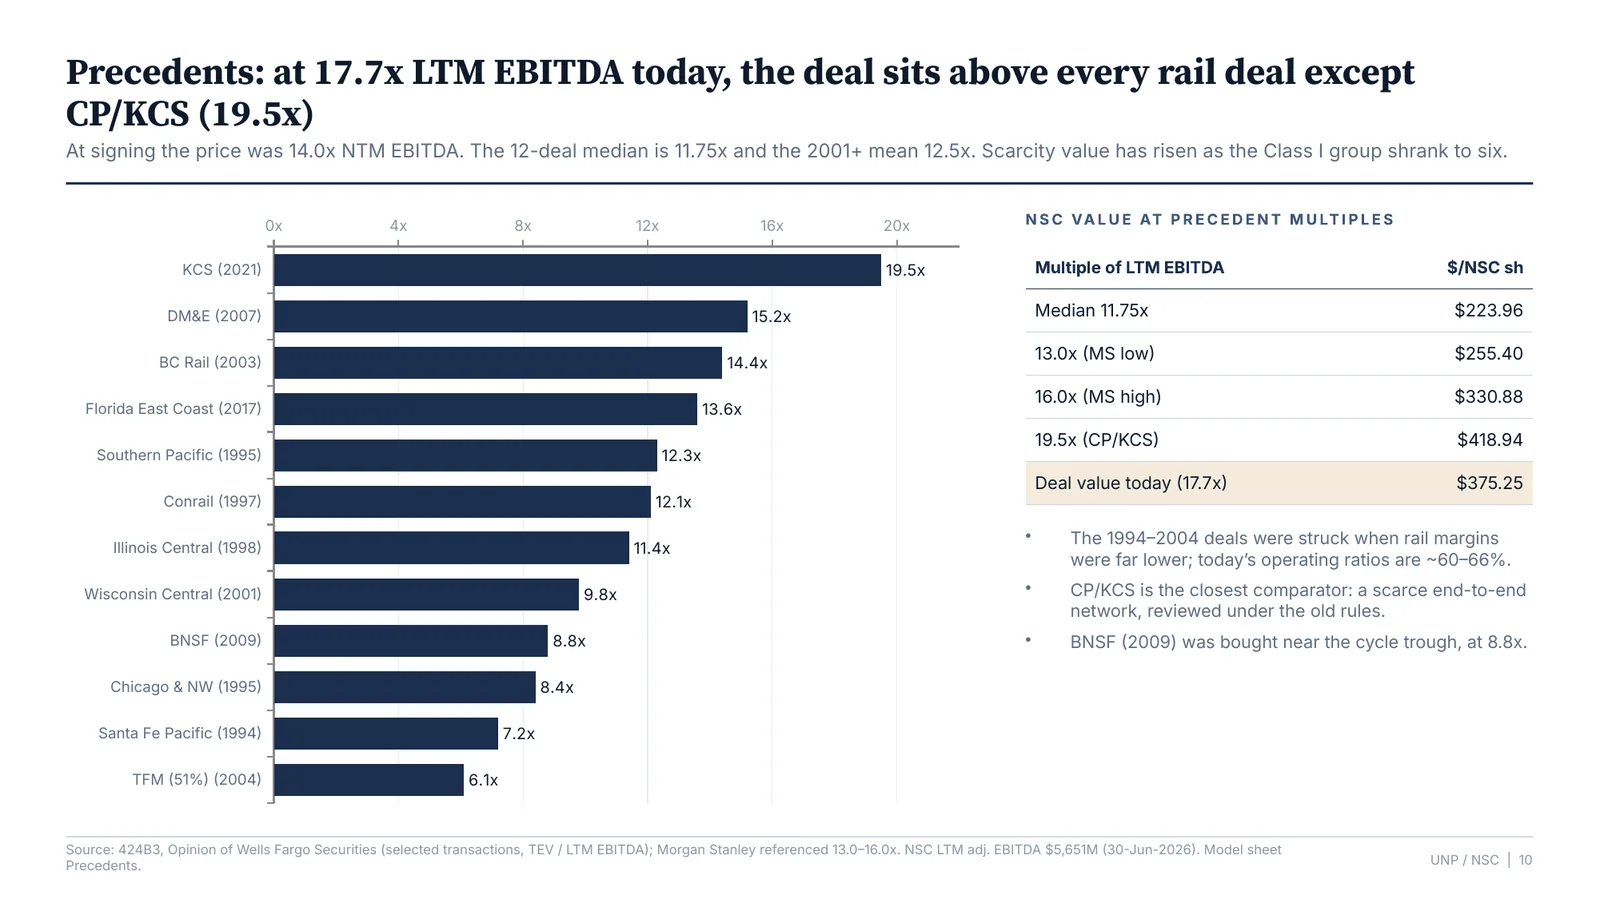
| Precedents: 12-deal median 11.75x LTM EBITDA | $223.96 |
| Precedents: 13.0-16.0x (Morgan Stanley range) | $255.40-$330.88 |
| Advisor DCFs ex-synergies (mid-2025) | MS $274-342; WF $270-350 |
| Deal value today | $375.25 |
Class I peers trade at 14.7x-17.1x LTM EBITDA (CSX 16.2x, CPKC 17.1x, CN 14.7x; UNP 15.6x). Private BNSF, at UNP’s multiple, would be worth ~$177B of EV. The deal’s 17.7x is above every rail precedent except CP/KCS (19.5x, 2021); BNSF (2009) went for 8.8x near the cycle trough. Our UNP DCF is $261.68 (-8.6% vs the price), so both stocks trade on terminal multiples above our 14.5x; the merger question turns on the relative numbers.
4. Synergies against the premium
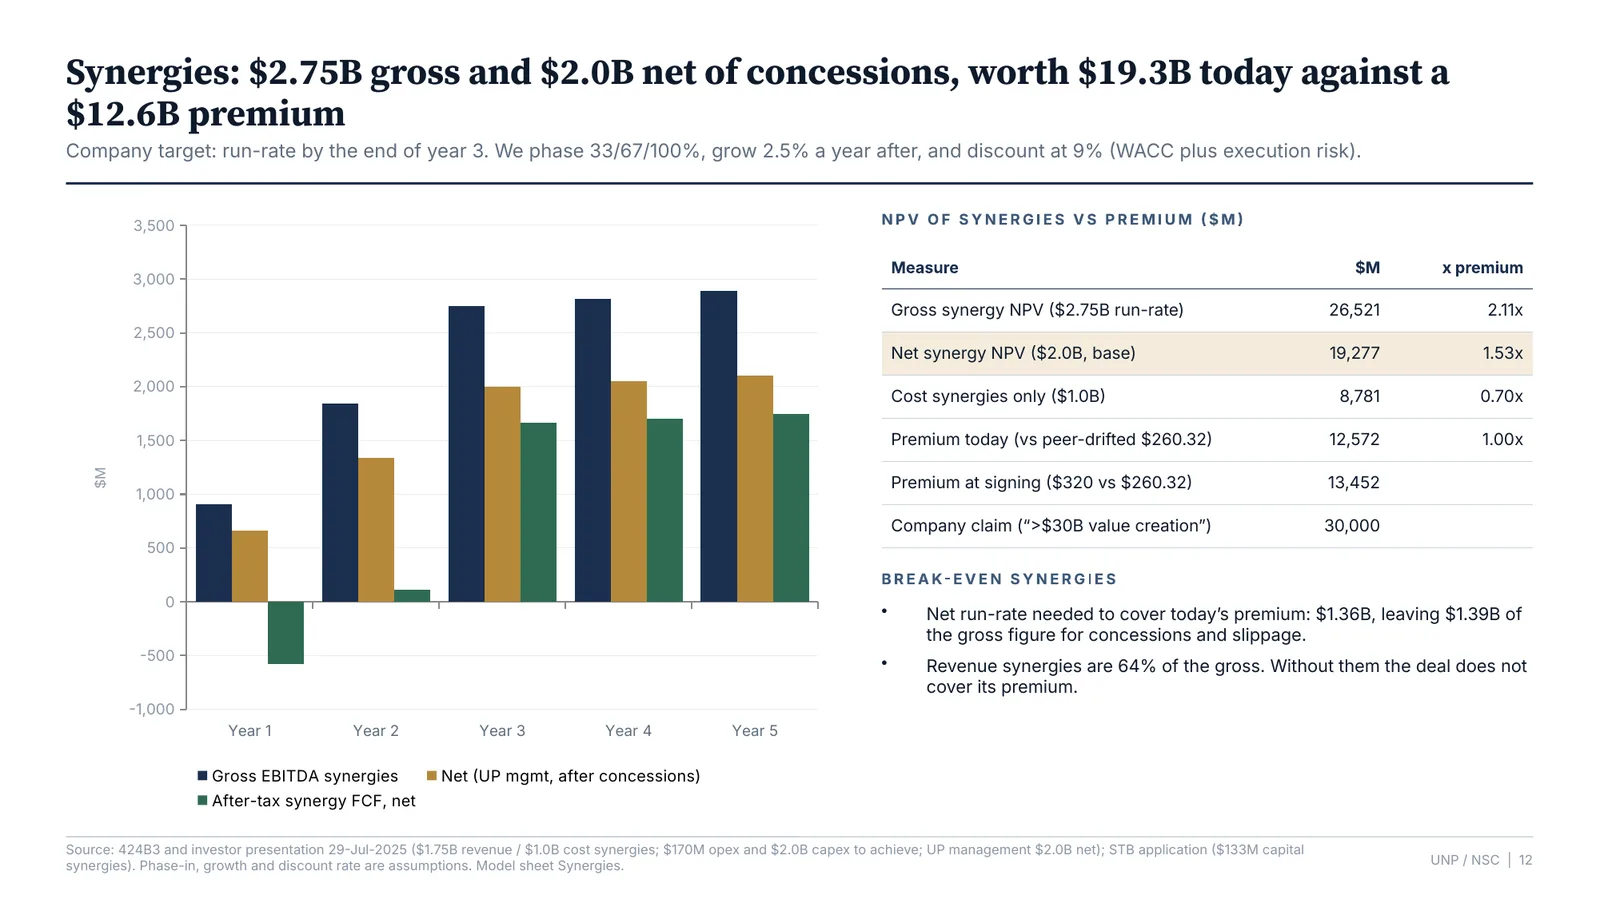
Management targets $2.75B of EBITDA synergies by the end of year 3 ($1.75B revenue, $1.0B cost), with $170M of operating cost and $2.0B of capex to achieve. UP management’s case nets this to $2.0B after illustrative concessions. Phasing 33/67/100% (assumption), growing 2.5% after year 3 and discounting at 9%:
| Measure | $M | x premium |
|---|---|---|
| Gross synergy NPV ($2.75B) | 26,521 | 2.11x |
| Net synergy NPV ($2.0B) | 19,277 | 1.53x |
| Cost synergies only ($1.0B) | 8,781 | 0.70x |
| Premium today (vs peer-drifted unaffected) | 12,572 | 1.00x |
| Premium at signing | 13,452 |
Net run-rate synergies of $1.36B cover today’s premium, leaving $1.39B of the gross figure for concessions and slippage.
5. What UNP shareholders get
A has/gets on our DCFs: UNP holders keep 72.5% of (UNP $155.5B + NSC $69.4B + net synergies $19.3B - cash and costs $20.2B) = $162.3B, against $155.5B standalone. Value created: $6.9B, $11.56 per share (+4.4%). With no synergies they would lose $8.4B; at the full $2.75B they would gain $21.17 per share.
Adjusted EPS accretion (close 31-Oct-2027; new debt at 5.75%, an assumption):
| 2028 | 2029 | 2030 | |
|---|---|---|---|
| Base ($2.0B net) | -1.2% | +5.2% | +9.4% |
| No synergies | -5.4% | -2.9% | -1.8% |
| Gross $2.75B | +0.4% | +8.2% | +13.6% |
| GAAP-style (illustrative step-up D&A) | -5.2% | +1.4% | +5.9% |
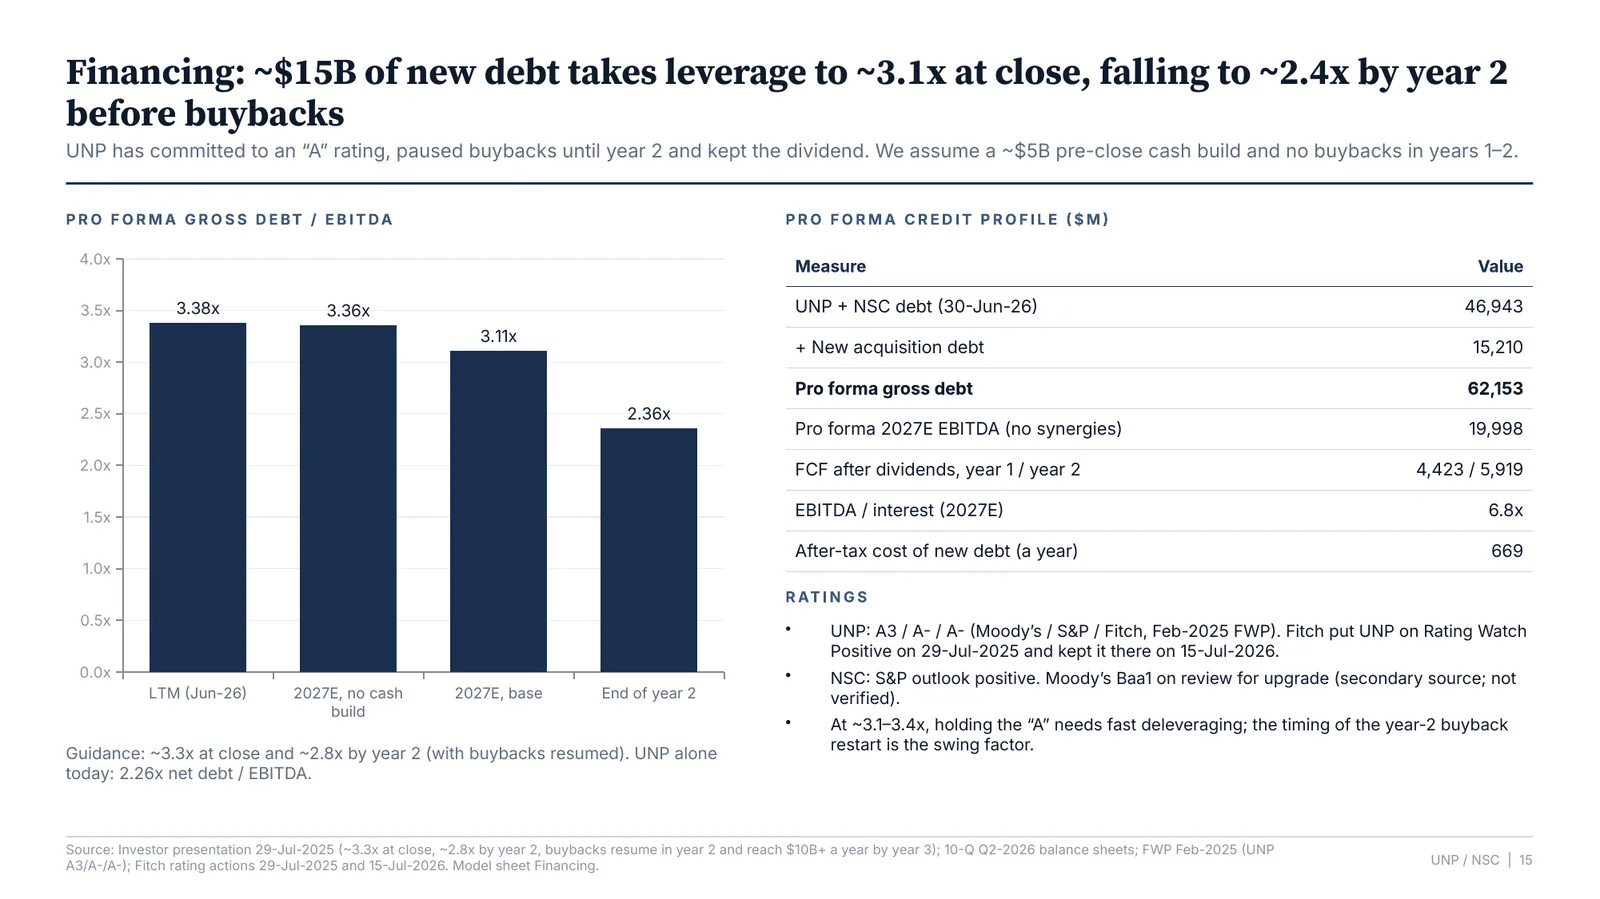
Financing and ratings. Pro forma gross debt is ~$62.2B: 3.38x LTM EBITDA, 3.11x on 2027E and 2.36x by the end of year 2 before buybacks (guidance: ~3.3x at close, ~2.8x by year 2). UNP is A3/A-/A- and committed to an “A” rating; Fitch has it on Rating Watch Positive. NSC’s ratings status comes from secondary sources.
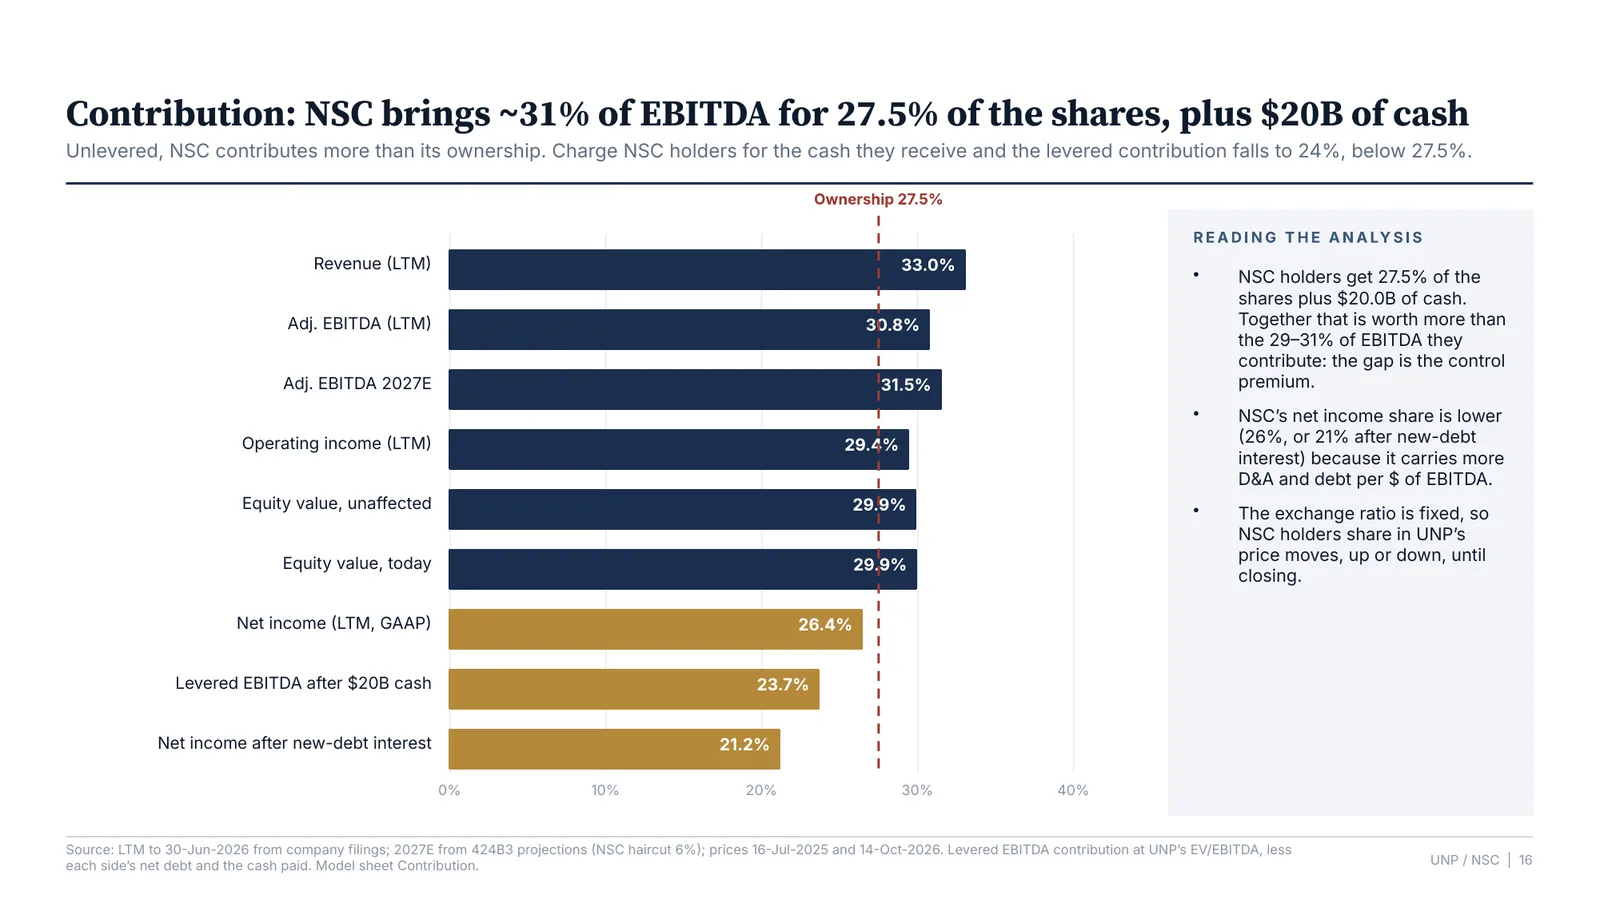
Contribution. NSC brings 33.0% of revenue and 30.8% of LTM EBITDA for 27.5% of the shares, plus $20.0B in cash. Charged for that cash, its levered EBITDA contribution is 23.7%: the control premium.
6. The STB review is the swing factor
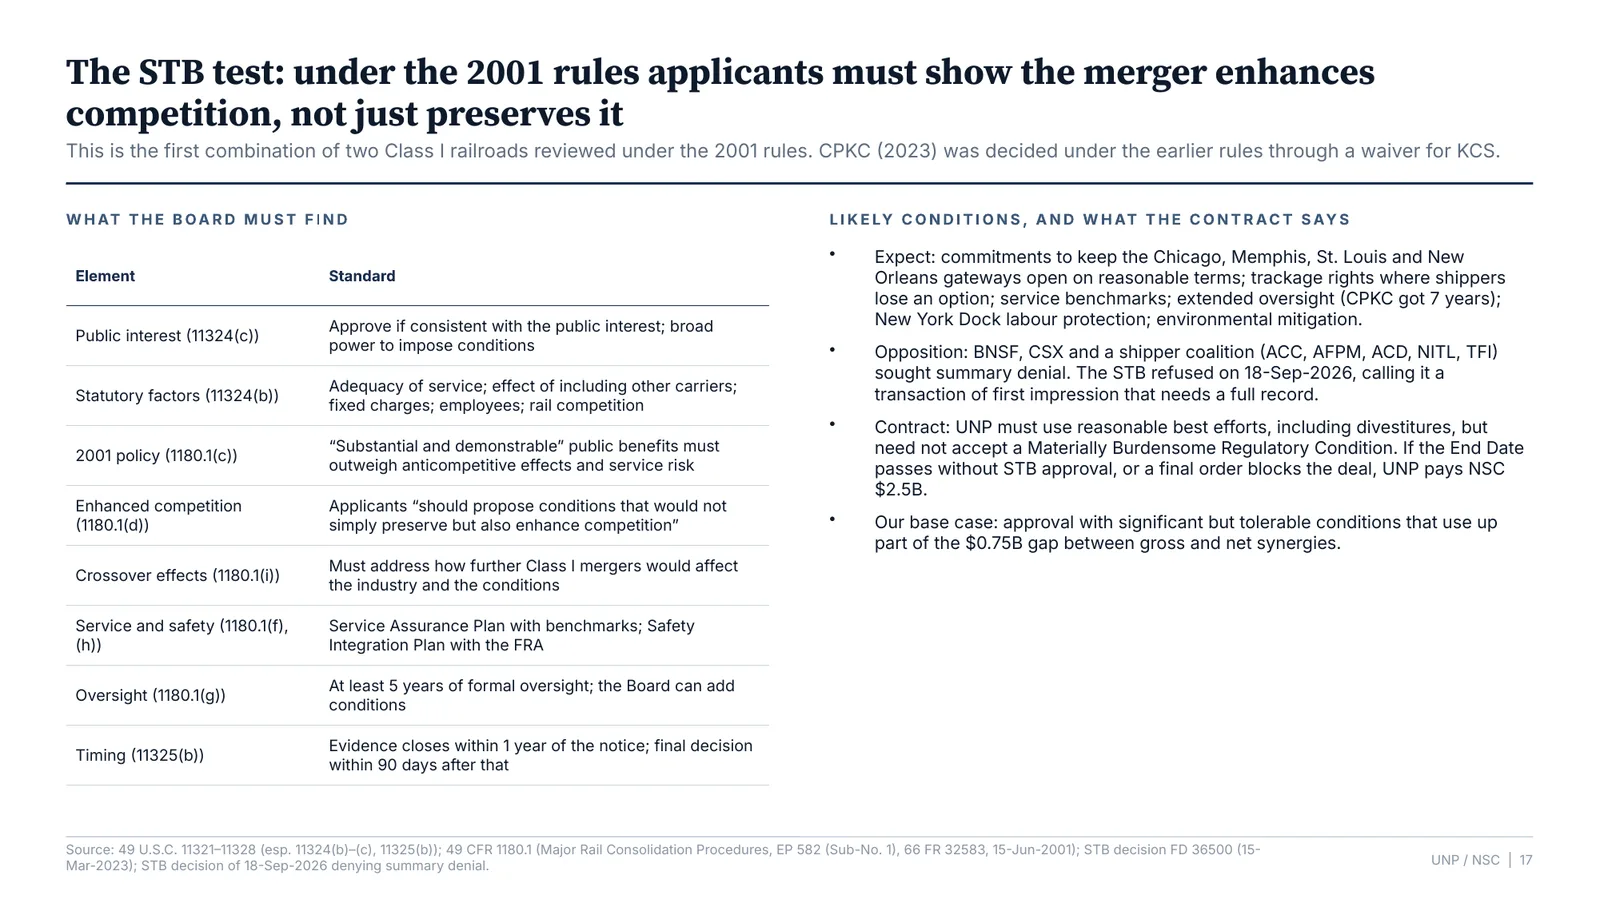
This is the first combination of two Class I railroads under the STB’s 2001 rules (49 CFR 1180.1). The Board must find the deal consistent with the public interest (49 U.S.C. 11324), and the 2001 policy requires “substantial and demonstrable” benefits and conditions that “would not simply preserve but also enhance competition”. Applicants must also address the crossover effects of further consolidation, file Service Assurance and Safety Integration Plans, and accept at least five years of oversight.
| Date | Step |
|---|---|
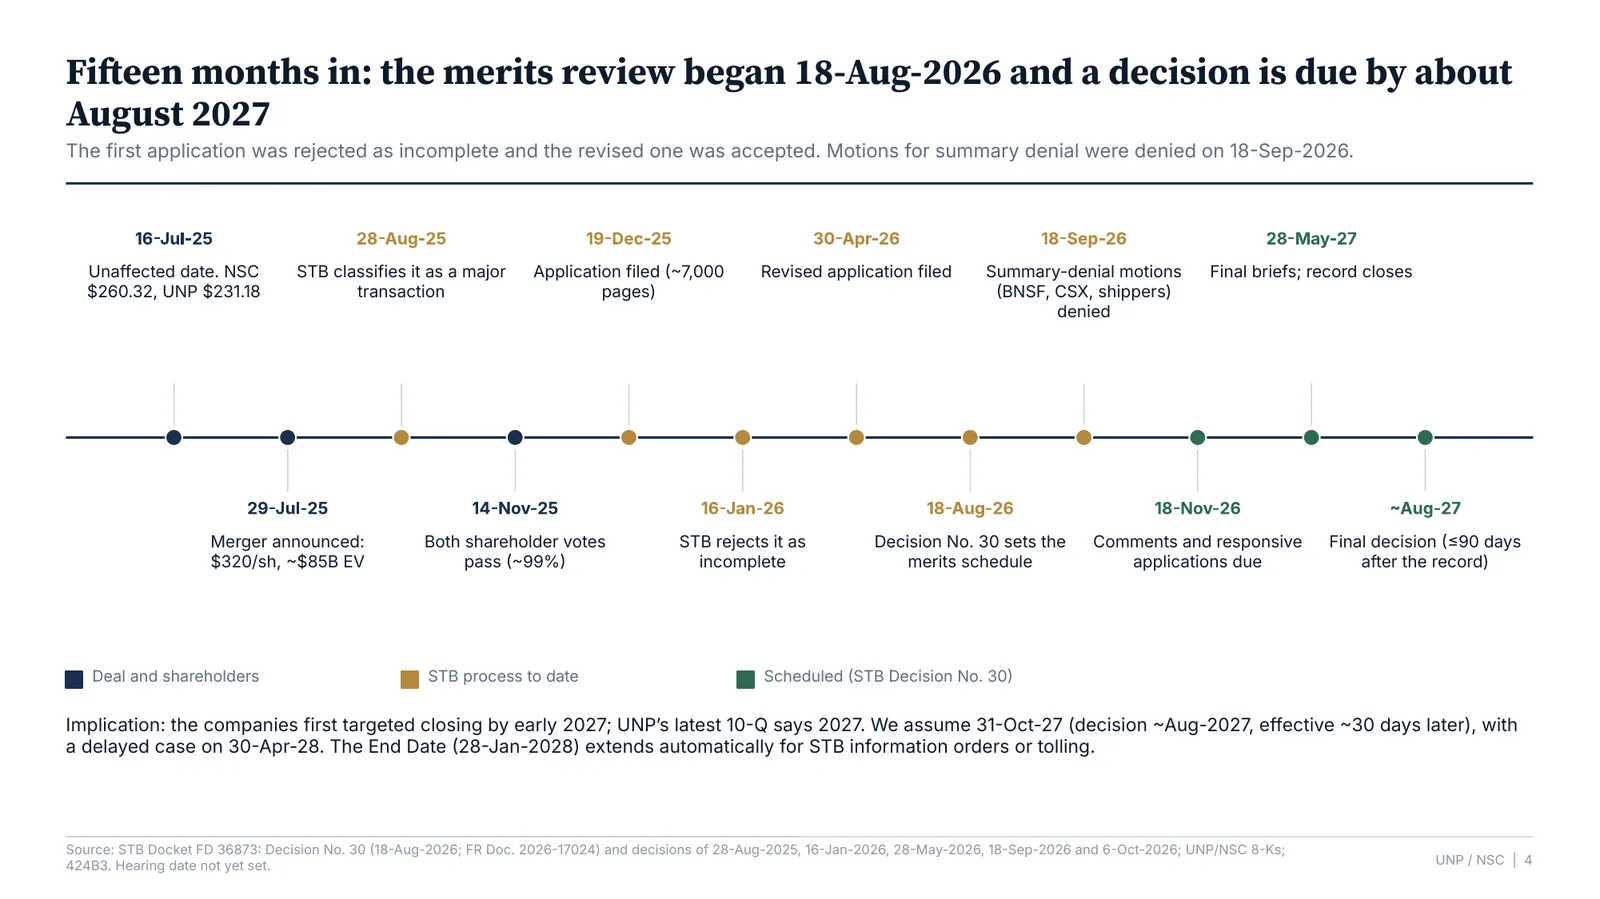
| 19-Dec-2025 | Application filed; rejected as incomplete 16-Jan-2026 |
| 30-Apr-2026 | Revised application; accepted 28-May-2026 |
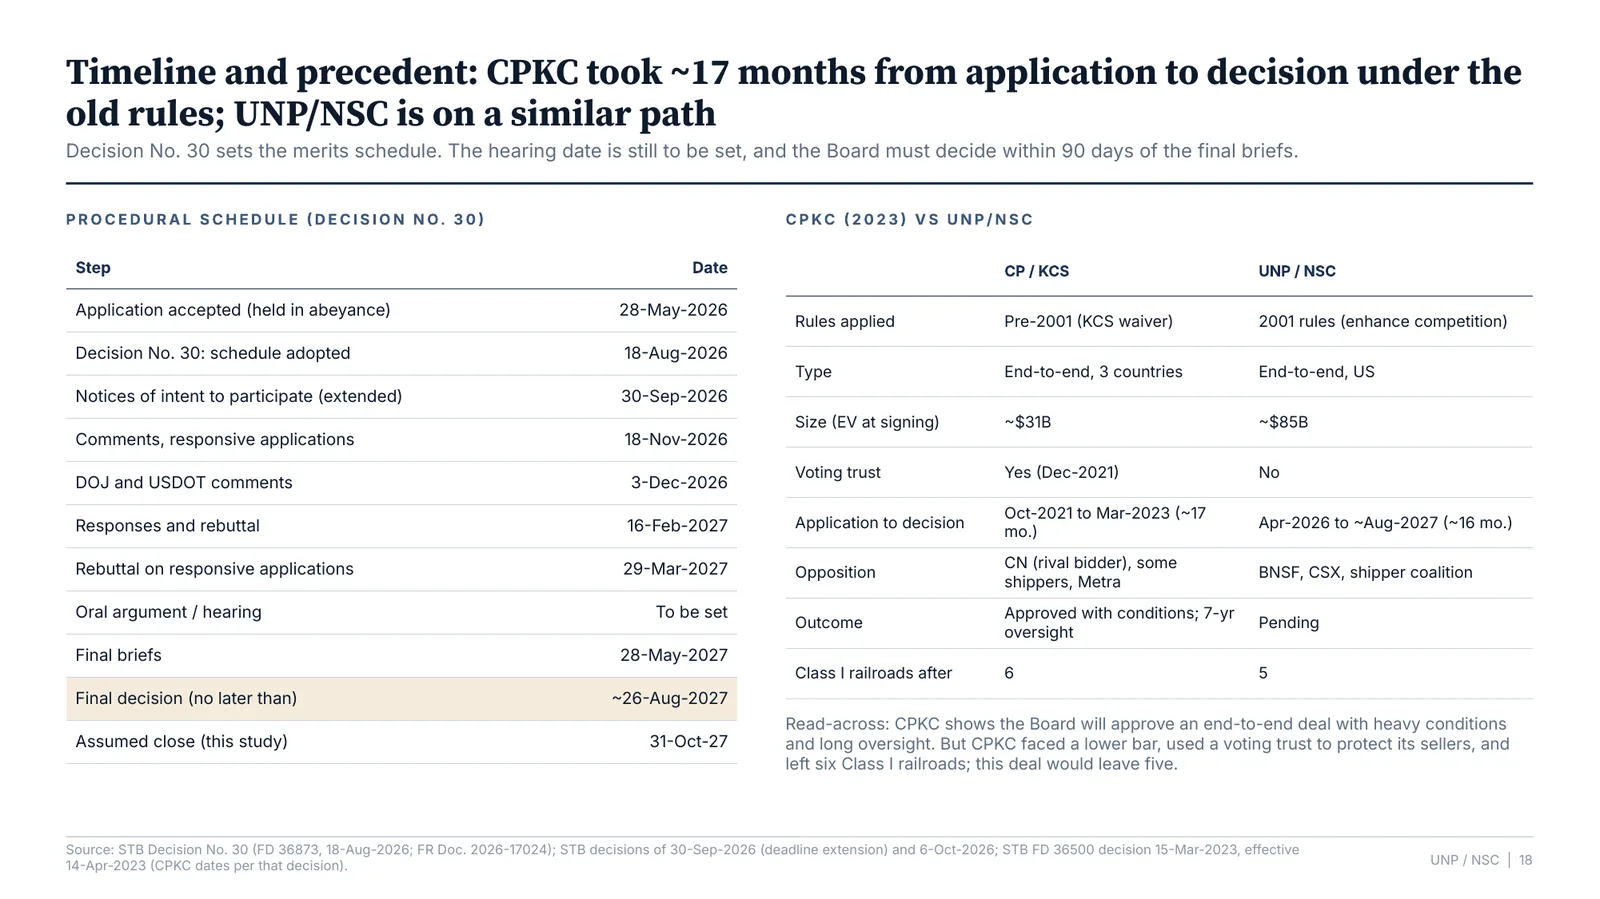
| 18-Aug-2026 | Decision No. 30 sets the merits schedule |
| 18-Sep-2026 | Summary-denial motions by BNSF, CSX and a shipper coalition denied |
| 18-Nov-2026 | Comments and responsive applications due |
| 3-Dec-2026 | DOJ and USDOT comments |
| 28-May-2027 | Final briefs (hearing date to be set) |
| ~26-Aug-2027 | Final decision due (90 days after the record) |
| 31-Oct-2027 | Assumed close (this study) |
Likely conditions: gateway commitments at Chicago, Memphis, St. Louis and New Orleans; trackage rights where shippers lose an option; service benchmarks and extended oversight (CPKC got seven years); New York Dock labour protection. CPKC precedent: approved with conditions in March 2023, about 17 months after its application, but under the pre-2001 rules, with a voting trust, leaving six Class I railroads. This deal faces a higher bar and would leave five.
7. The spread and what it implies
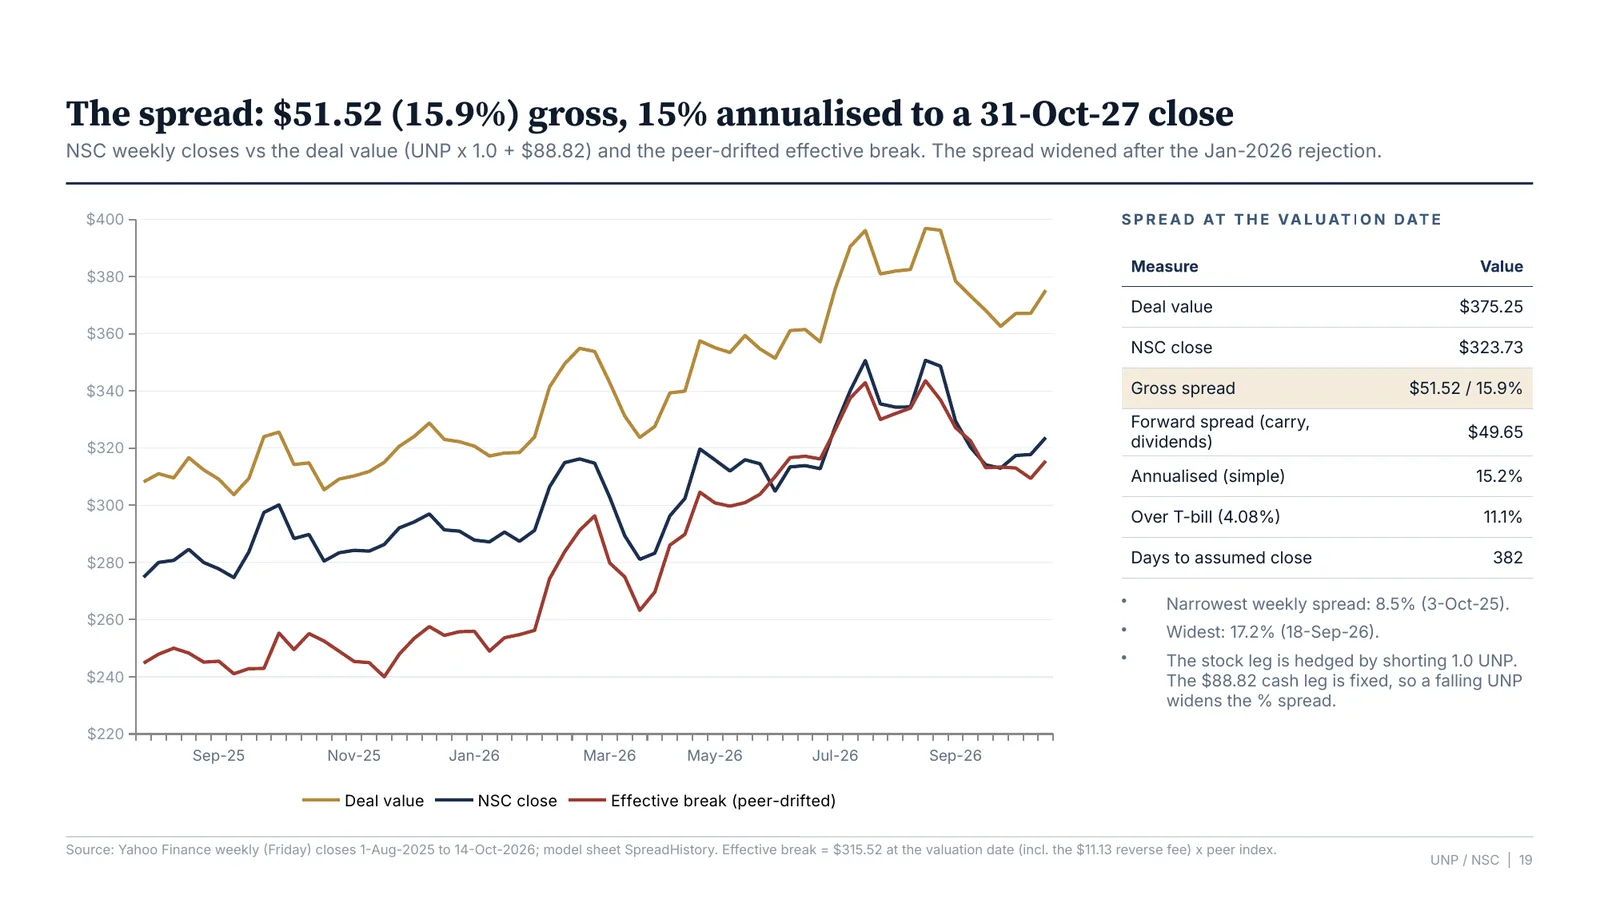
| Measure | Value |
|---|---|
| Deal value / NSC close | $375.25 / $323.73 |
| Gross spread | $51.52 (15.9%); 15.2% annualised to 31-Oct-2027 |
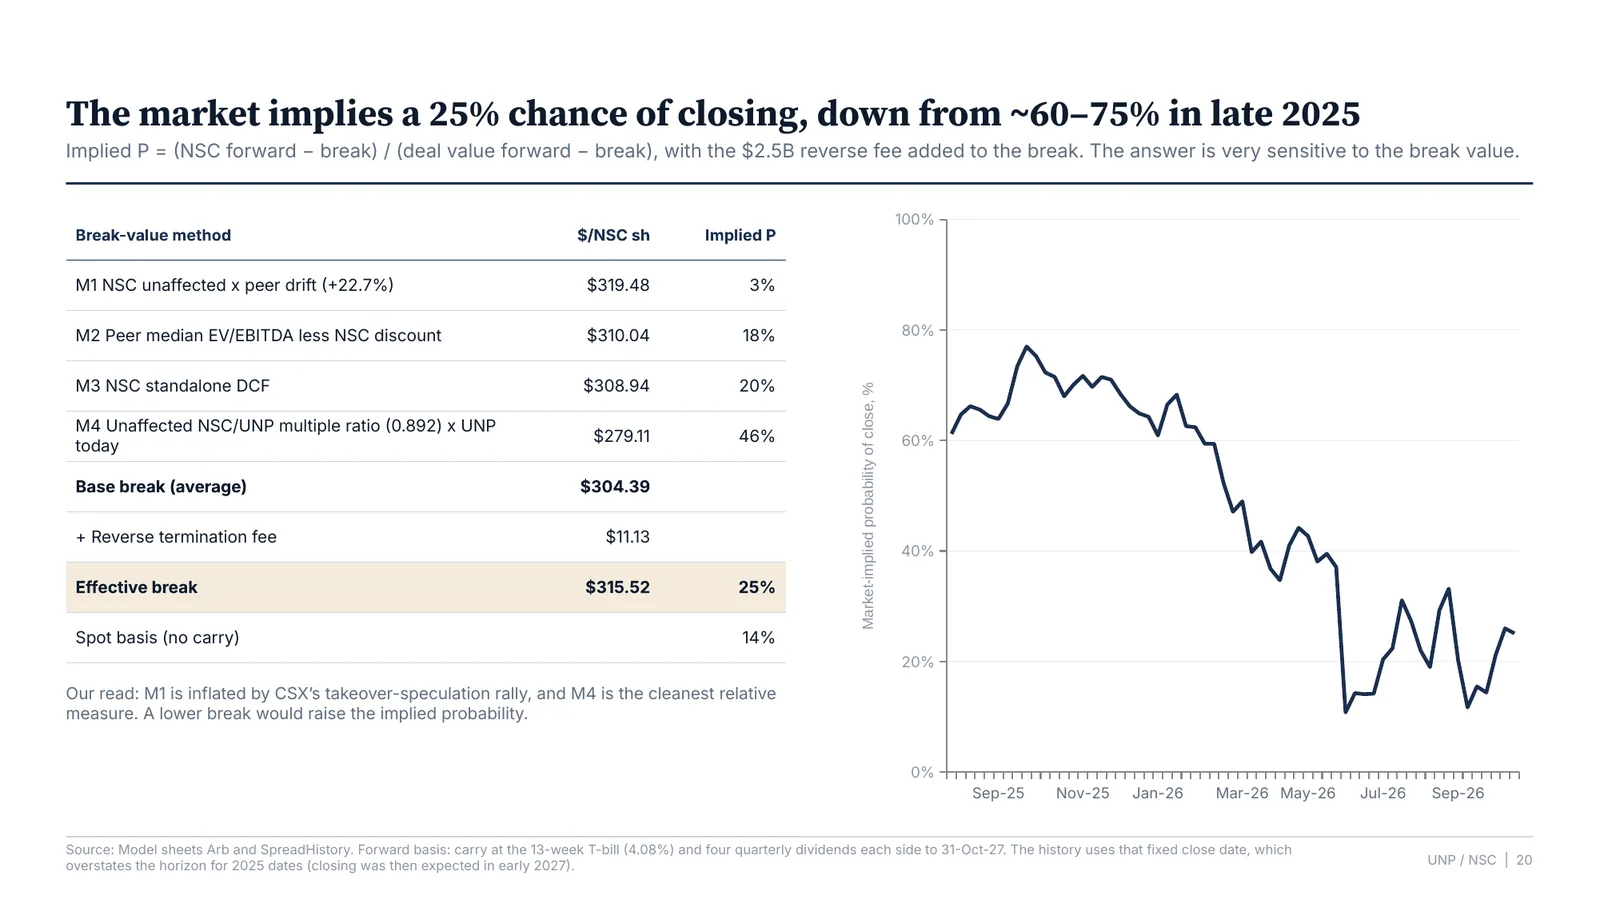
| Break value: average of four methods | $304.39 (range $279.11-$319.48) |
| Effective break (+ $11.13 reverse fee) | $315.52 |
| Market-implied P(close), forward basis | 25% (14% spot) |
The four break methods are NSC’s unaffected price drifted with CSX/CPKC/CN ($319.48), peer EV/EBITDA less NSC’s discount ($310.04), NSC’s DCF ($308.94) and the unaffected NSC/UNP multiple ratio applied to UNP today ($279.11). The implied probability was ~60-75% in late 2025 and fell after the January 2026 rejection.
8. Scenarios and the trade
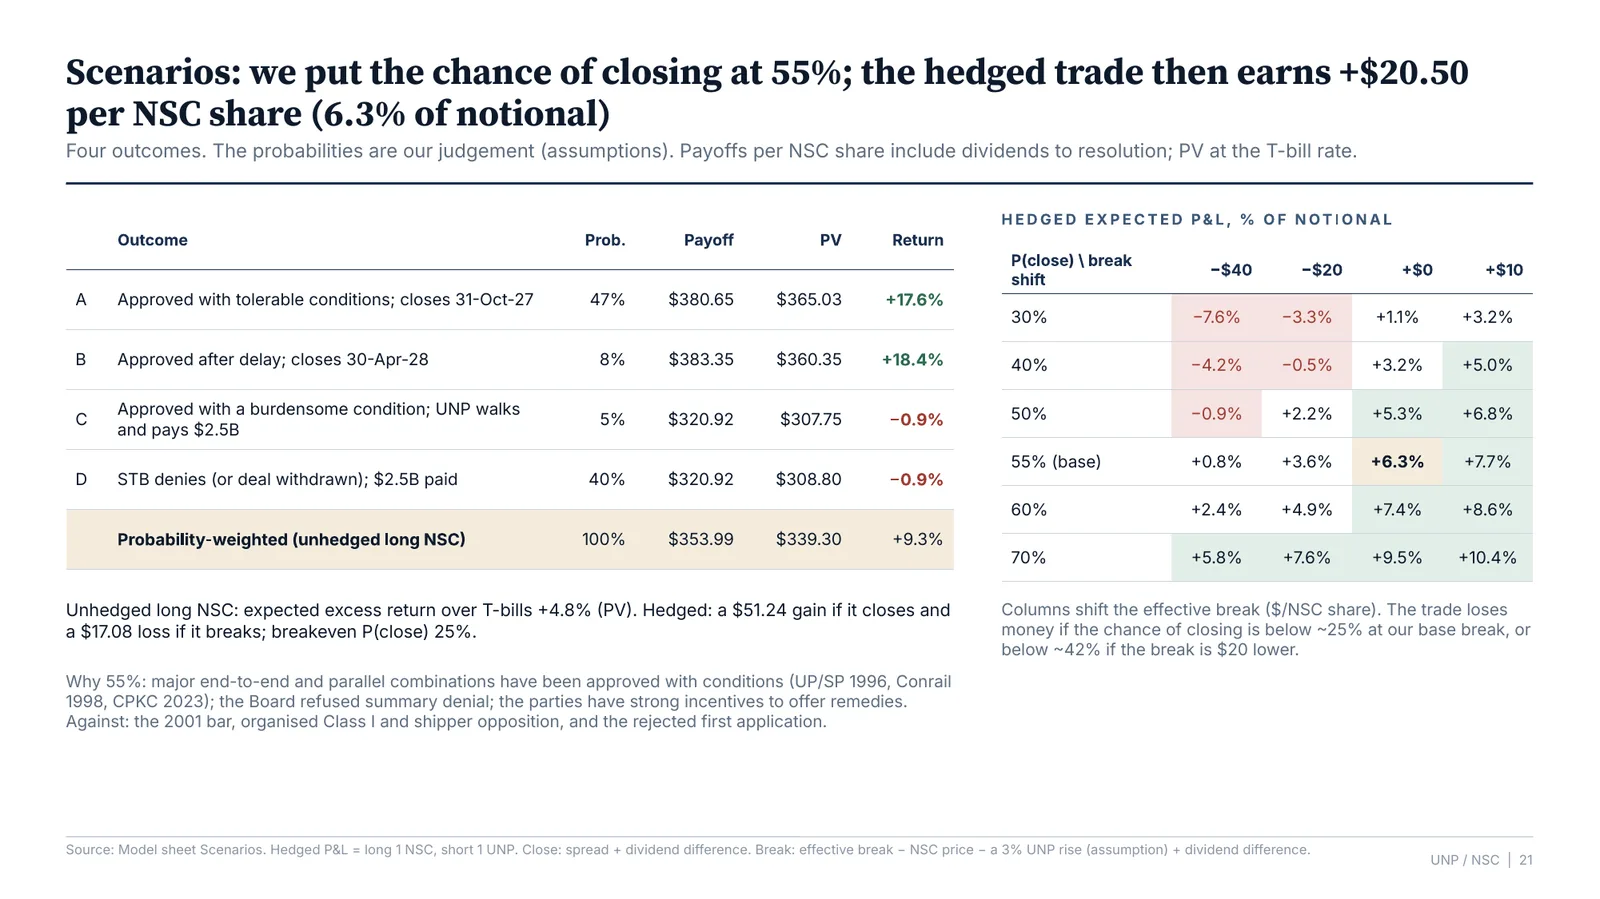
| Scenario | Prob. | Payoff/NSC sh | Return |
|---|---|---|---|
| A. Approved with tolerable conditions; closes 31-Oct-2027 | 47% | $380.65 | +17.6% |
| B. Approved after delay; closes 30-Apr-2028 | 8% | $383.35 | +18.4% |
| C. Burdensome condition; UNP walks and pays $2.5B | 5% | $320.92 | -0.9% |
| D. STB denies; $2.5B paid | 40% | $320.92 | -0.9% |
| Probability-weighted (unhedged) | 100% | $353.99 | +9.3% |
Probabilities are our judgement. Hedged (long 1 NSC, short 1 UNP): $51.24 if it closes, -$17.08 if it breaks (assuming UNP rises 3% on a break); breakeven 25%; expected $20.50 (6.3% of notional). The trade loses money only if the chance of closing is below ~25% at our base break, or below ~42% if the break is $20 lower. Size: 9.5% of NAV long notional, so a break costs 0.5% of NAV and a close adds ~1.5%.
9. Risks
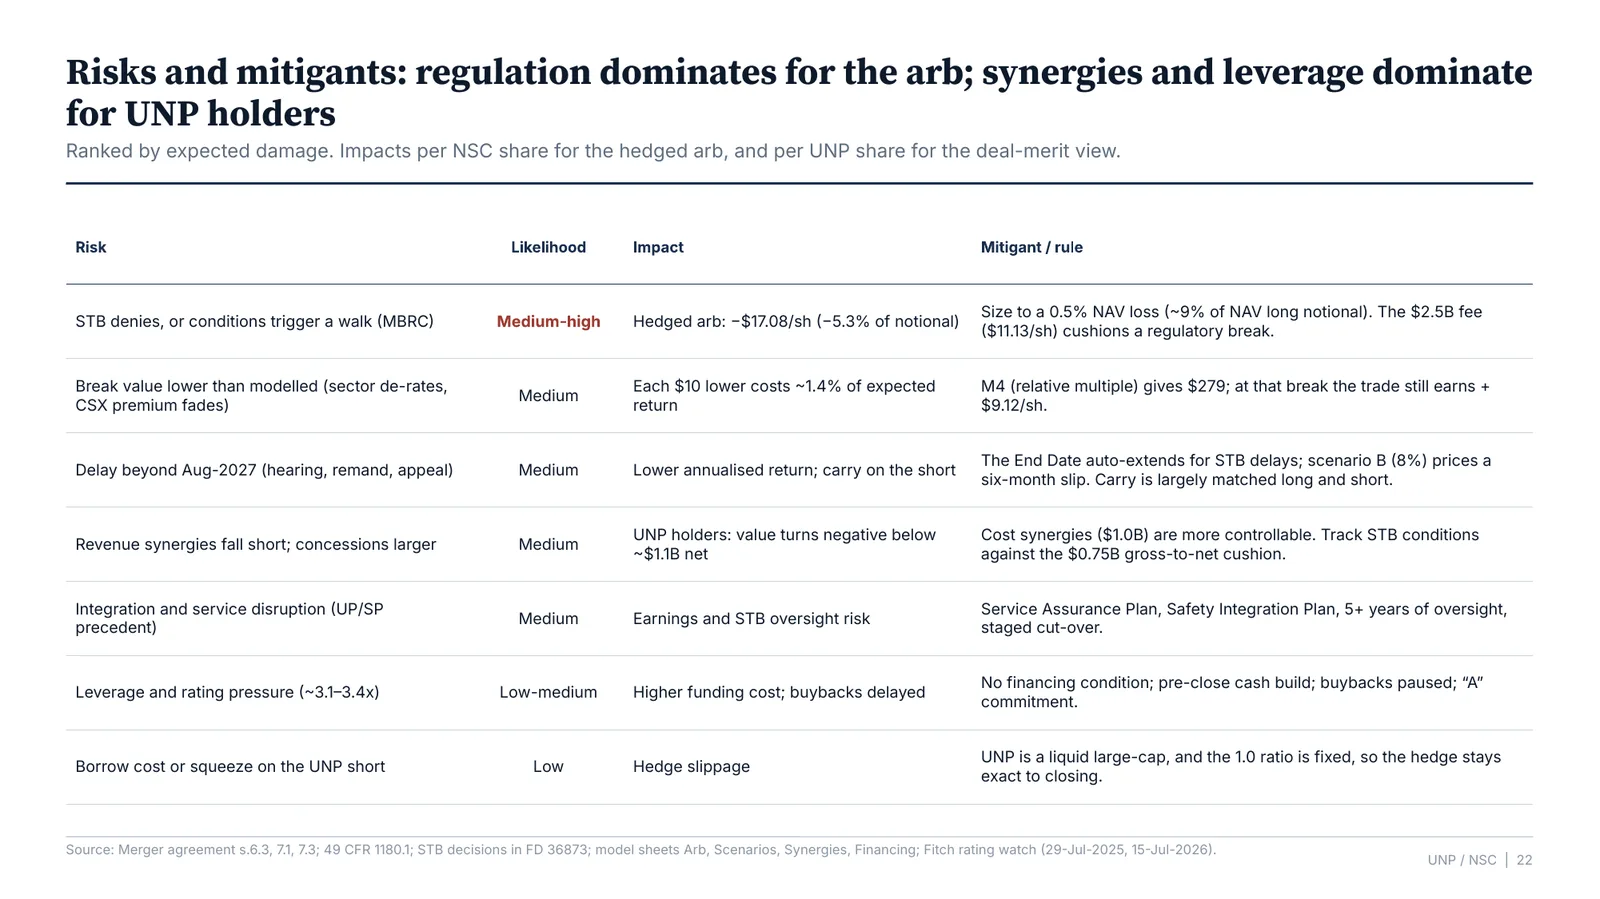
- STB denial or a walk-away condition (medium-high): -$17.08/share hedged; the $2.5B fee cushions it, and sizing caps the loss at 0.5% of NAV.
- Lower break value (sector de-rating, CSX premium fading): at the $279.11 low-end break the trade still earns +$9.12/share.
- Delay beyond August 2027: the End Date auto-extends for STB delays; scenario B prices a six-month slip.
- Revenue synergies short, concessions larger: value to UNP holders turns negative below ~$1.1B of net synergies.
- Integration and service disruption, and leverage at ~3.1-3.4x with an “A” commitment.
10. What would change our mind
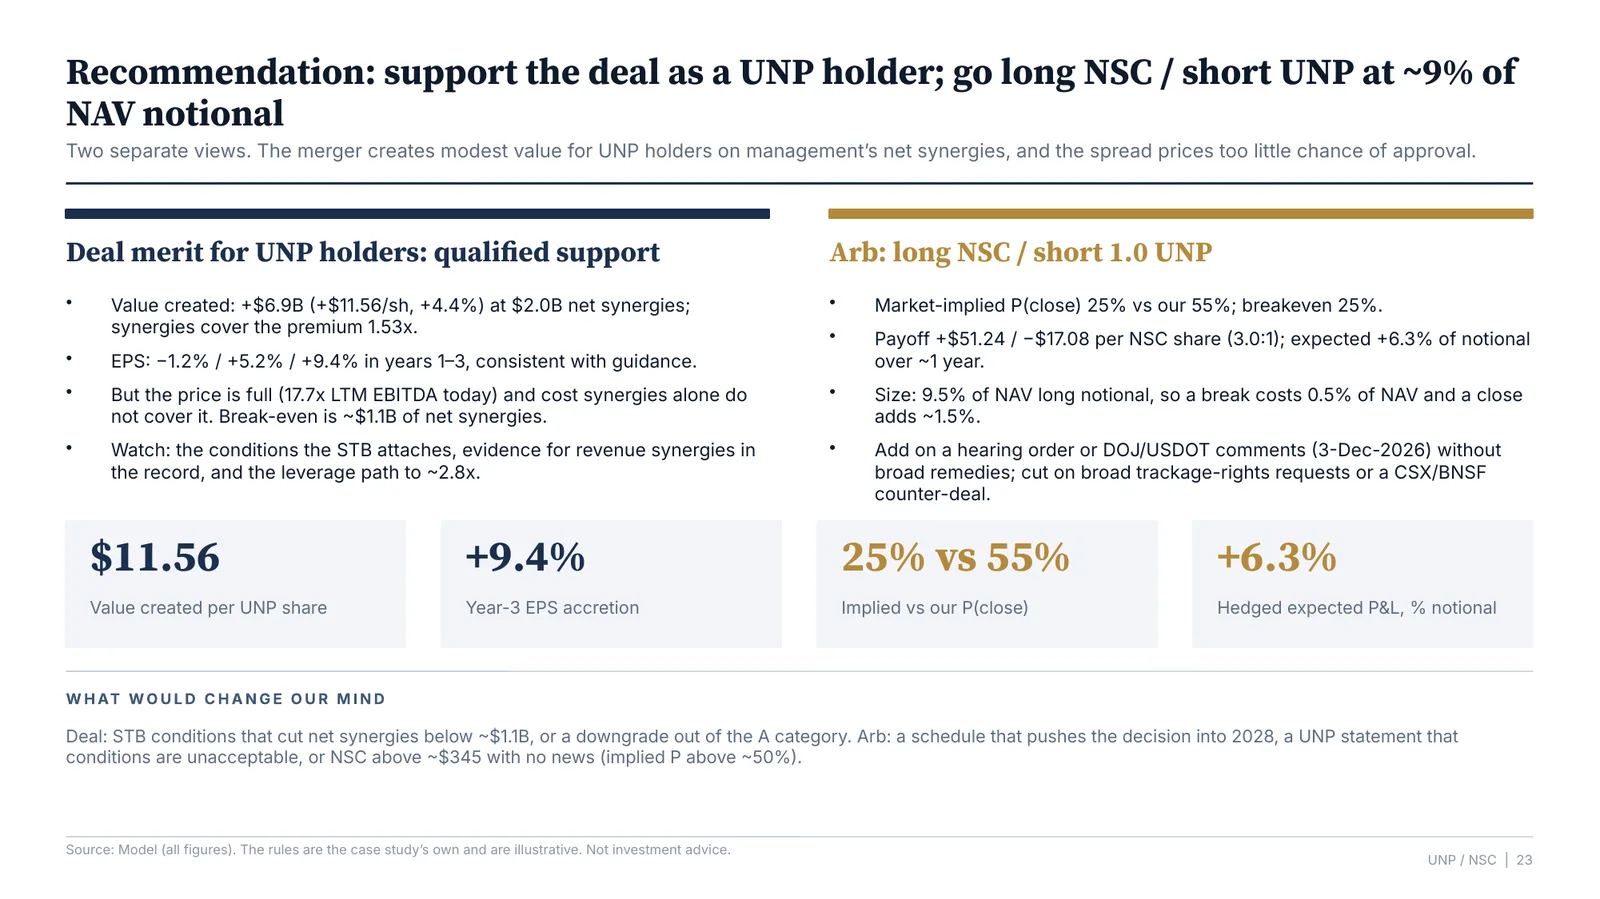
- Deal merit: STB conditions that cut net synergies below ~$1.1B, or a downgrade out of the A category.
- Arb: a schedule that pushes the decision into 2028, a UNP statement that conditions are unacceptable, or broad trackage-rights remedies backed by DOJ/USDOT. Add on a hearing order or DOJ/USDOT comments without broad remedies; take profit if NSC trades above ~$345 with no news (implied P above ~50%).
What could not be verified
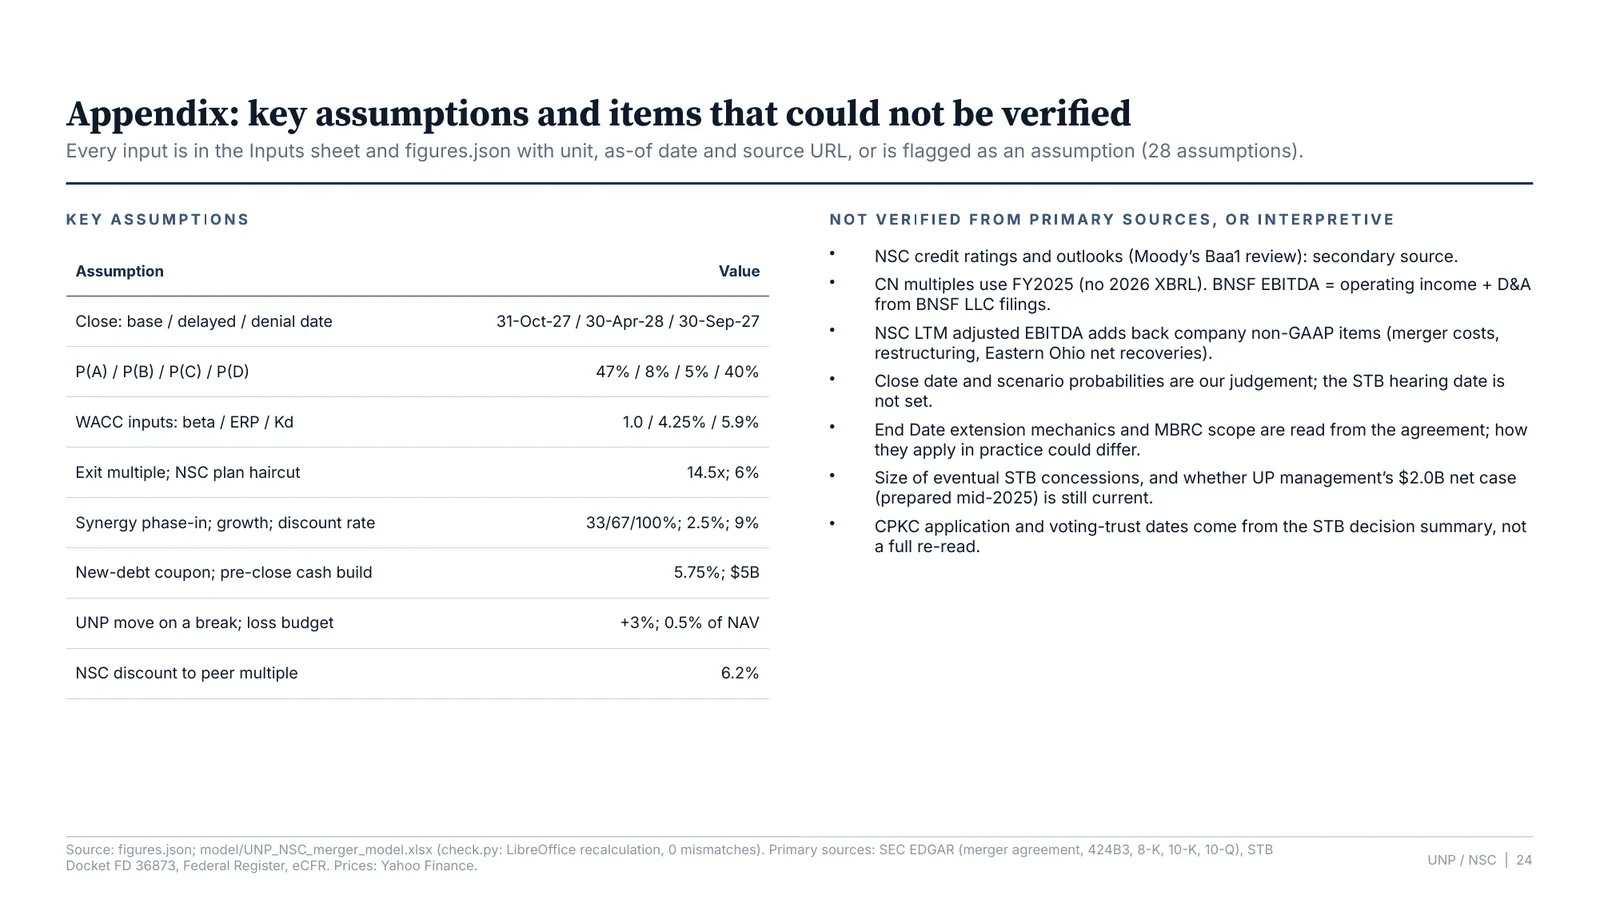
- NSC credit ratings and outlooks (Moody’s Baa1 review; S&P positive outlook) are from secondary sources.
- CN multiples use FY2025 (no 2026 XBRL). BNSF EBITDA is operating income plus D&A from BNSF Railway LLC filings.
- NSC LTM adjusted EBITDA adds back company non-GAAP items (merger costs, restructuring, Eastern Ohio net recoveries).
- The close date and all scenario probabilities are our judgement; the STB hearing date is not set.
- End Date extension mechanics and the scope of a Materially Burdensome Regulatory Condition are our reading of the agreement.
- The size of STB concessions, and whether UP management’s $2.0B net case (prepared mid-2025) is still current.
- CPKC dates come from the STB decision summary.